

Why No Credit Check Equipment Financing Is Changing Business Growth
No credit check equipment financing lets businesses get essential equipment without traditional credit approval, but true “no credit check” options are rare – most legitimate lenders still perform soft credit pulls or use alternative approval methods.
Quick Answer for “No Credit Check Equipment” Searches:
- What it really means: Approval based on equipment value, business revenue, or sales history instead of credit scores
- Approval speed: 24 hours to instant decisions
- Common requirements: Bank statements, equipment quotes, valid ID
- Rates: Start at 3.25% for qualified applicants
- Terms: 24-84 months with seasonal payment options
The biggest challenge small business owners face isn’t finding equipment – it’s getting approved for financing when banks focus heavily on personal credit scores. Traditional equipment loans can take weeks and require perfect credit, leaving growing businesses stuck without the tools they need.
But here’s what most business owners don’t know: the equipment itself often serves as collateral, making lenders more flexible with credit requirements. Some programs approve 80% of applicants, while others offer instant digital cards for immediate equipment purchases.
I’m Vincent Cerniglia, and through Noreast Capital Corporation, I’ve helped businesses nationwide secure equipment financing when traditional banks said no. My experience with no credit check equipment programs has shown me that the right financing structure can get essential equipment into your business within 24-48 hours, regardless of your credit history.
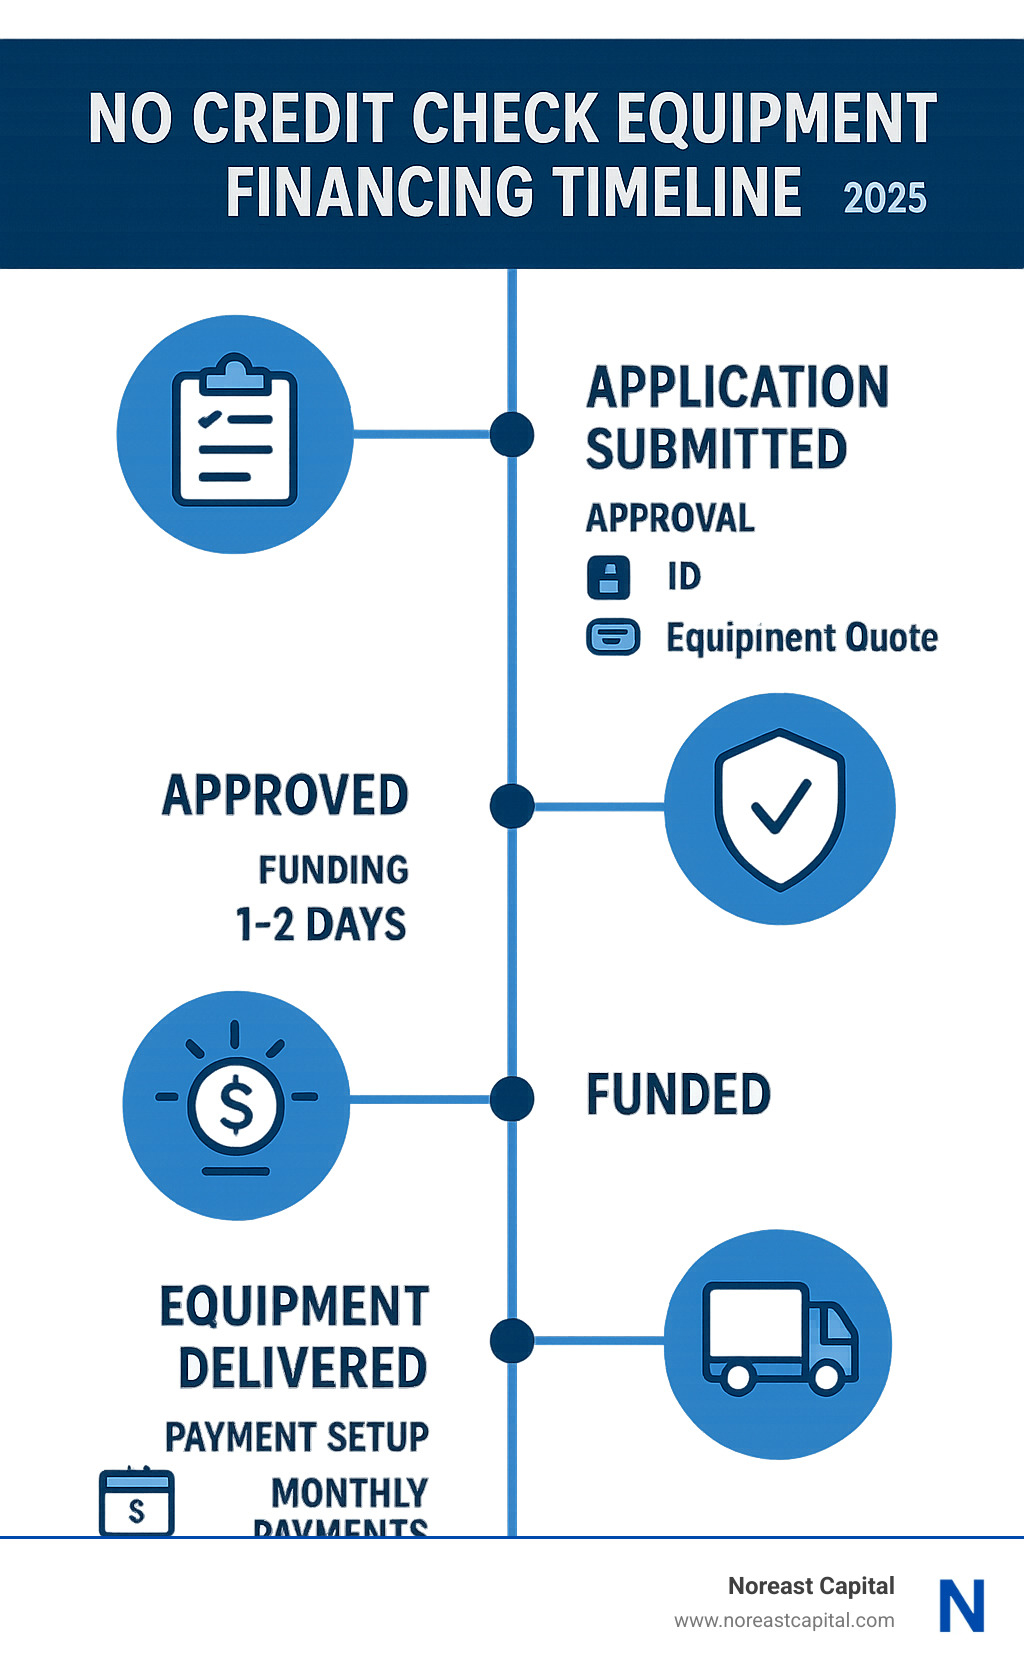
No credit check equipment terms simplified:
Why This Guide Matters
Cash flow challenges affect 82% of small businesses, and traditional financing often makes the problem worse. When you need equipment to grow but can’t qualify for bank loans, your business gets stuck in a catch-22: you need equipment to generate revenue, but you need good credit to get equipment.
Startups face even bigger problems. Most banks require 2+ years in business and perfect credit scores, leaving new businesses without options when they need equipment most.
Understanding No Credit Check Equipment Financing
Let’s clear something up right away: no credit check equipment financing isn’t completely “no credit check” – but it’s pretty close to it. Most legitimate lenders will do a quick peek at your credit (called a soft pull), but they won’t base their entire decision on what they find there.
Think of it this way: instead of your credit score being the star of the show, the equipment itself takes center stage. The lender looks at the equipment as collateral – something valuable they can recover if things go sideways.
The approval speed is where these programs really shine. Most decisions happen within 2-4 hours using soft credit pulls that won’t ding your credit score. Some lenders even offer instant decisions through their online applications.
What Is “no credit check equipment” Financing?
Here’s the honest truth about no credit check equipment financing: it’s become a bit of a marketing term that doesn’t quite match reality anymore. True “no questions asked” financing disappeared from the legitimate lending world years ago.
What these programs actually offer is credit-flexible financing where your credit score takes a backseat to other factors. Instead of obsessing over your FICO score, lenders focus on things that actually matter for equipment financing: the equipment’s value and condition, your business revenue and cash flow, your bank account history, and whether you can put money down.
The equipment itself serves as the primary collateral, which is why lenders can be so much more flexible. If you can’t make payments, they can recover the equipment – it’s that simple.
How Does No Credit Check Equipment Work?
The process is refreshingly straightforward compared to traditional bank loans. Most programs start with application-only approval for amounts up to $500,000. Higher amounts might require some financial statements, but even then, it’s usually just basic bank statements.
Some lenders take it a step further with digital card issuance – they’ll provide you with a virtual debit card right after approval so you can buy equipment immediately.
Lease-to-own structures are common, letting you build toward ownership over 12-84 months. Many programs also offer deferred payment options, giving you up to 90 days after equipment delivery before your first payment is due.
The real game-changer is the speed: 24-hour approvals are standard for most applications under $250,000.
| Feature | No Credit Check Programs | Traditional Equipment Loans |
|---|---|---|
| Credit Score Requirement | Flexible (500+) | Good to Excellent (650+) |
| Approval Time | 24-48 hours | 2-4 weeks |
| Documentation | Minimal | Extensive |
| Down Payment | 0-10% | 10-20% |
| Interest Rates | 3.25%-18% | 5%-12% |
What Can You Finance? Eligible Equipment & Industries
The beauty of no credit check equipment financing is its flexibility – we’ve helped businesses across dozens of industries get the tools they need to grow. From a small bakery upgrading their ovens to a construction company adding their fifth excavator, the equipment itself becomes your pathway to approval.
Most programs offer 100% financing, which means you’re not just covering the equipment cost. Installation fees, freight charges, taxes, and even training costs can roll into your monthly payment.

Construction equipment dominates our financing volume – excavators, bulldozers, concrete mixers, and scaffolding systems. Medical practices find success financing diagnostic equipment, dental chairs, imaging systems, and surgical tools.
Restaurant and food service businesses benefit enormously from equipment financing. Commercial ovens, walk-in refrigeration, POS systems, and prep equipment can transform a struggling kitchen into a profit center. Lawn care professionals use financing for commercial mowers, trimmers, trucks, and trailers.
Software and technology financing has exploded recently. POS systems, accounting software, CRM platforms, and even website development can qualify under the right programs. Used equipment often approves faster than new purchases since the depreciation curve is already established.
The key requirement is simple: your equipment must have resale value to serve as collateral.
Lease-to-Own Lawn Mowers (Example)
Seasonal businesses face unique cash flow challenges, and lawn care is the perfect example. You need expensive commercial mowers before your busy season starts, but your revenue disappears during winter months.
Lease-to-own lawn mower programs solve this perfectly. Instead of spending $15,000-$50,000 upfront on commercial equipment, you start with monthly payments as low as $200-$400. The equipment works for you immediately, generating revenue from day one.
The real game-changer is seasonal payment structures. Your payments adjust to match your revenue – higher during busy spring and summer months, then reduced payments during winter when work slows down.
More info about Lease-to-Own Lawn Mowers No Credit Check
Restaurant & Food-Service Essentials
Restaurant equipment financing addresses one of the food service industry’s biggest barriers: massive upfront costs for essential equipment. A complete commercial kitchen setup can easily cost $100,000 or more, but financing spreads this investment over 24-84 months while your kitchen generates revenue.
Commercial ovens and ranges ($5,000-$25,000) often top the priority list. Walk-in refrigeration systems ($8,000-$30,000) come next, since food safety depends on proper temperature control. POS and payment processing equipment ($2,000-$10,000) has become essential as customers expect modern payment options.
More info about Bad Credit Restaurant Equipment Leasing
Who Qualifies & How to Apply Without Stress
Getting approved for no credit check equipment financing is refreshingly straightforward compared to traditional bank loans. You won’t need perfect credit, extensive financial statements, or weeks of patience while underwriters debate your application.
Most programs welcome businesses that have been operating for just 6-12 months, though some accept startups with strong revenue projections. The sweet spot for approval is $10,000+ in monthly revenue – that’s $120,000 annually, which many small businesses reach within their first year.
You’ll need an active business bank account to show cash flow patterns, plus a valid business license if your state requires one. The final piece is an equipment quote from your vendor.
The application process moves at internet speed rather than bank speed. Most decisions happen within 2-4 hours, and funding typically completes in 1-2 business days.

Qualifying for a “no credit check equipment” Program
Here’s where no credit check equipment programs get creative. Instead of obsessing over that credit score from five years ago, they look at what your business is actually doing today.
Bank account history tells a much better story than old credit reports. Lenders can see your daily deposits, seasonal patterns, and cash flow consistency.
Payment processing history is pure gold for approval. If you process payments through systems like PayPal or Square, that transaction history proves your business generates real revenue from real customers.
Industry experience matters more than you’d think. A mechanic applying for automotive equipment financing brings credibility that a credit score can’t capture.
The equipment itself provides security for the loan. A $50,000 excavator holds its value better than an unsecured personal loan, which reduces the lender’s risk and increases your approval odds.
Required Documents & Speed-to-Funding
The paperwork requirements are refreshingly minimal. You’ll need your driver’s license or state ID for identity verification.
A voided business check or recent bank statement shows your account details and recent activity. This replaces the mountain of financial statements traditional lenders demand.
Your equipment quote or invoice from the vendor tells lenders exactly what you’re buying and its market value.
The completed application with e-signature capability wraps everything together. Digital signatures eliminate the printing, signing, scanning, and emailing dance that slows down traditional financing.
Speed advantages transform the financing experience. Digital document submission means no overnight mail delays. Automated underwriting systems work 24/7, not just during banker’s hours.
Rates, Terms, Fees & Early Payoff Rules
Understanding the true cost of no credit check equipment financing can feel overwhelming, but it’s actually pretty straightforward once you know what to look for. The key is matching payment terms to your business’s cash flow patterns rather than just chasing the lowest rate.
Interest rates typically start at 3.25% for strong businesses with solid revenue and equipment that holds its value well. However, rates can climb to 18% if your business is newer or the equipment is specialized.
Payment terms usually range from 24 to 84 months, giving you plenty of flexibility to match payments with your business cycle. Construction companies might choose longer terms to keep payments manageable during winter months, while restaurants might prefer shorter terms to own their equipment faster.
Seasonal payment programs are game-changers for businesses with fluctuating revenue. Landscaping companies can make higher payments during busy spring and summer months, then reduce payments during winter.
Deferred payment options let you start generating revenue before payments begin. Most programs offer 90-day deferrals, perfect for businesses that need time to install equipment and ramp up operations.
Factor rates appear frequently in equipment financing. A 1.1 factor rate means you pay back $1.10 for every $1.00 borrowed. Always ask lenders to convert factor rates to annual percentage rates (APR) for easier comparison.
Early payoff options vary by lender, but most allow penalty-free prepayment. This flexibility lets you pay off equipment faster when business is good, saving on interest costs.
According to Federal Reserve research, small businesses perform better when payment structures align with revenue cycles rather than forcing fixed monthly payments.
The bottom line? Focus on total cost and payment flexibility rather than just the interest rate. Equipment financing should help your business grow, not create financial stress.
Pros, Cons, Risks & Red-Flag Scams
Let’s be honest about no credit check equipment financing – it’s not perfect, but it can be a game-changer for businesses that need equipment fast. Understanding both sides helps you make the right decision for your situation.
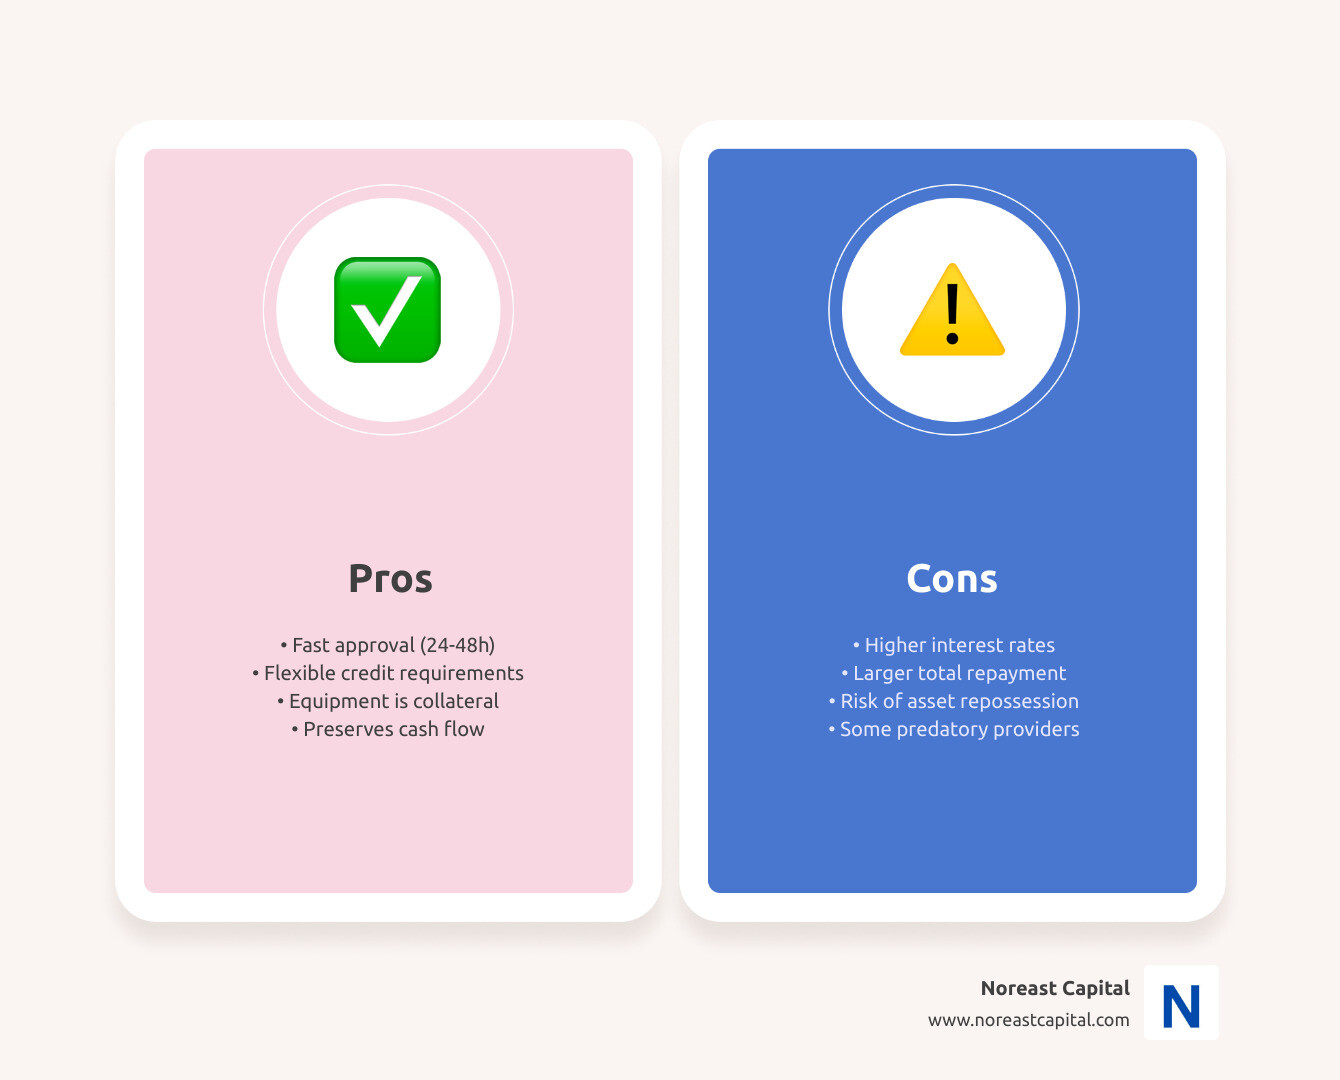
The biggest advantage is speed – when your business needs equipment this week, not next month, these programs deliver. Most approvals happen within 24-48 hours, and you can often get funding the same week.
Your credit flexibility opens doors that banks keep locked. A 580 credit score that disqualifies you at the bank might be perfectly fine for equipment financing, especially if your business generates steady revenue.
Cash flow preservation might be the most valuable benefit. Instead of draining your business account for a $50,000 piece of equipment, you spread that cost over 3-5 years while the equipment generates revenue.
Some programs help build business credit when you make payments on time. This creates a pathway to better financing terms in the future.
But here’s where it gets tricky – higher costs are almost guaranteed compared to traditional bank loans. While banks might offer 5-8% rates, equipment financing often runs 8-18% or higher.
The equipment repossession risk is real. Since your equipment secures the loan, defaulting means losing the tools your business depends on.
Shorter repayment terms in some programs mean higher monthly payments. A bank might offer 7-year terms while some equipment programs max out at 3-4 years.
How to Spot a Scam
The no credit check equipment space attracts some shady characters who prey on desperate business owners. I’ve seen too many businesses get burned by obvious scams that could have been avoided.
Upfront fees are the biggest red flag. Legitimate lenders make money from interest and payments, not from charging you $500-$2,000 before they even approve your application.
Wire transfer requests should trigger alarm bells. Scammers love wire transfers because they’re nearly impossible to reverse. Real lenders use ACH transfers, checks, or direct deposits to verified business accounts.
Companies with no physical address or proper licensing operate in the shadows for good reason. Legitimate lenders have real offices, proper state licenses, and verifiable business credentials.
“Guaranteed approval” promises regardless of your situation are mathematically impossible. Even the most flexible programs decline some applications.
Pressure tactics that demand immediate signatures without review time are classic scam behavior. Legitimate lenders want you to understand the terms and succeed with your financing.
Legitimate lenders never charge upfront fees, provide clear terms with total cost breakdowns, hold proper state and federal licenses, and allow time for document review.
Alternatives & Credit-Building Strategies
Sometimes no credit check equipment financing isn’t the perfect fit for your business situation. Don’t worry – you have several other paths to get the equipment you need while potentially improving your credit along the way.
Equipment leasing offers a middle ground between no-credit-check programs and traditional bank loans. Most leasing companies want to see moderate credit (around 600+) and typically require 10-20% down payment, but they offer competitive rates and terms up to 84 months.
For smaller equipment needs, microloans provide an interesting option. They offer loans up to $15,000 with no minimum credit score requirements. The application process takes longer but can be worth the wait if you’re not in a rush.
SBA 504 loans deserve consideration for larger equipment purchases, especially when combined with real estate. These government-backed programs require only 10% down payment and offer below-market interest rates. The application process takes longer (4-8 weeks), but the savings can be substantial for qualified businesses.
Merchant cash advances provide the fastest funding – often within 24 hours – based entirely on your credit card sales history. However, they’re expensive with factor rates of 1.2-1.5, which translates to 40-60% APR. Use these only for emergency equipment needs when speed matters more than cost.
While you’re exploring financing options, consider strategies to strengthen your credit profile for better terms in the future. Pay down existing debt to improve your credit utilization ratios – even small improvements can open up better rates. Dispute any errors on your credit reports, as these mistakes are surprisingly common and can drag down your scores unfairly.
Building business credit takes time but pays dividends. Add trade references from suppliers who report to business credit bureaus. Consider asking someone with strong credit to co-sign your application, or offer additional collateral beyond just the equipment to strengthen your position.
Many successful businesses start with higher-cost financing to get essential equipment running, then refinance to better terms as their credit and cash flow improve over 12-18 months. Think of it as a stepping stone rather than a permanent solution.
More info about Equipment Financing with No Money Down
The key is getting the right equipment in your business today so you can start generating the revenue and credit history that opens doors to better financing tomorrow.
Frequently Asked Questions about No Credit Check Equipment Financing
Let’s tackle the most common questions business owners ask about no credit check equipment financing. These answers come from real experience helping thousands of businesses get the equipment they need.
Do these programs help build business credit?
Here’s the honest truth: it depends on which lender you choose. Some no credit check equipment financing companies report your payment history to business credit bureaus like Dun & Bradstreet, Experian Business, and Equifax Business. Others don’t bother with reporting at all.
Always ask upfront whether your payments will be reported to business credit agencies. This question alone can help you choose between similar programs. If building business credit matters to your long-term goals, make reporting a requirement in your decision process.
The good news is that consistent, on-time payments can significantly boost your business credit profile, especially if you’re a newer company. We’ve seen businesses go from having no credit history to qualifying for traditional bank loans within 12-18 months of establishing positive payment patterns.
But here’s the flip side – missed payments get reported too. If you’re struggling to make payments, that negative history will follow your business credit profile for years. So only take on payments you’re confident you can handle.
How fast can I get the funds?
Speed is one of the biggest advantages of no credit check equipment programs, but timing varies based on your loan amount and complexity.
For smaller amounts under $25,000, you might get funded the same day or next business day. These deals move fast because they’re lower risk and require minimal documentation.
Amounts between $25,000 and $100,000 typically take 24-48 hours from approval to funding. Most of this time is spent on paperwork processing and equipment verification, not underwriting decisions.
Larger amounts over $100,000 usually need 2-5 business days. The lender wants to verify equipment values and may require additional documentation for bigger commitments.
Here’s a neat feature some programs offer: digital debit cards issued immediately upon approval. You can start buying equipment right away while the formal paperwork processes in the background.
Can I pay off early without penalties?
Most legitimate no credit check equipment financing programs let you pay off early without penalties, but this isn’t universal. Always confirm early payoff terms before signing anything. This detail can save you thousands of dollars later.
Many lease-to-own programs actually offer discounts for early buyouts. Instead of paying the full remaining balance, you might pay 80-90% of what’s left. This creates a win-win situation – you save money, and the lender gets their principal back faster.
Let me give you a real example of how much early payoff can save. Say you finance $50,000 worth of equipment with a 1.3 factor rate over 36 months. If you pay it off after 18 months instead of the full term, you could save $5,000 to $8,000 in total financing costs.
The math works especially well for businesses that experience rapid growth or seasonal windfalls. Many of our clients use tax refunds, busy season profits, or contract bonuses to pay down equipment financing early.
Just remember to get the early payoff calculation in writing before you sign. Some programs calculate early payoff differently than others, and you want to know exactly what you’ll owe if you decide to pay off early.
Conclusion
Getting the equipment you need shouldn’t depend on a perfect credit score. No credit check equipment financing has helped thousands of businesses grow when traditional banks turned them away, but understanding what these programs actually offer makes all the difference.
Here’s what really matters: most legitimate lenders still check credit, but they don’t base their entire decision on your score. Instead, they look at your equipment’s value, your business revenue, and your ability to make payments. The equipment itself becomes your strongest qualification, not your past financial mistakes.
The approval speed advantage is real – while banks take weeks or months, equipment financing programs typically approve applications within 24-48 hours. Rates start at 3.25% for strong applicants, though they can reach 18% for higher-risk situations. That’s still often better than using credit cards or waiting months for traditional approval.
Your next steps are straightforward. Start by gathering your driver’s license, recent bank statements, and equipment quotes. Then research multiple lenders to compare their actual terms – not just their marketing promises. Apply to 2-3 programs to see your real options, but avoid submitting too many applications at once.
Read everything carefully before signing. Watch for upfront fees, wire transfer requests, or “guaranteed approval” promises that sound too good to be true. Legitimate lenders never charge fees before approval and always give you time to review terms.
At Noreast Capital, we’ve seen businesses transform within weeks of getting the right equipment. A small restaurant doubled their capacity with new ovens. A landscaping company went from manual labor to efficient machinery. The right equipment doesn’t just help you work – it helps you grow.
Don’t let credit challenges keep you stuck. The equipment your business needs is available, and there are legitimate ways to finance it even with imperfect credit. You just need to understand your options and work with the right financing partner.
The tools to grow your business are within reach. Take the first step and see what’s possible.