

No Credit Check Furniture: Get What You Need Today
No credit check lease to own furniture offers a fast solution for furnishing your home without traditional credit requirements. Here’s what you need to know:
- Instant Approval: Get approved for up to $5,000 in minutes with just valid ID, steady income, and a checking account
- No Credit History Required: Bad credit or no credit history won’t stop you from being approved
- Take Home Same Day: Select your furniture and bring it home immediately after approval
- Flexible Payments: Choose weekly, bi-weekly, or monthly payments that align with your payday
- Early Purchase Options: Save money with 90-day early purchase options at many retailers
With lease-to-own furniture, you make regular payments over time (typically 12 months) until you own the items outright. Unlike traditional financing, these programs consider factors beyond credit scores, making approval accessible to nearly everyone.
The application process is simple – most retailers offer online applications with instant decisions, or you can apply in-store while shopping. Initial payments are typically low ($10-$59), with free delivery and setup included by most providers.
I’m Vincent Cerniglia, and I’ve helped countless customers steer no credit check lease to own furniture options through my work at Noreast Capital, where we specialize in providing financing solutions that keep cash flow healthy while giving you access to the items you need.
No credit check lease to own furniture terms you need:
– lease to own benefits
– lease to own financing no credit check
No Credit Check Lease-To-Own Furniture Explained
Ever wondered how you can get that beautiful sofa or dining set without a credit check? No credit check lease-to-own furniture programs make it possible for almost anyone to furnish their home, regardless of credit history.
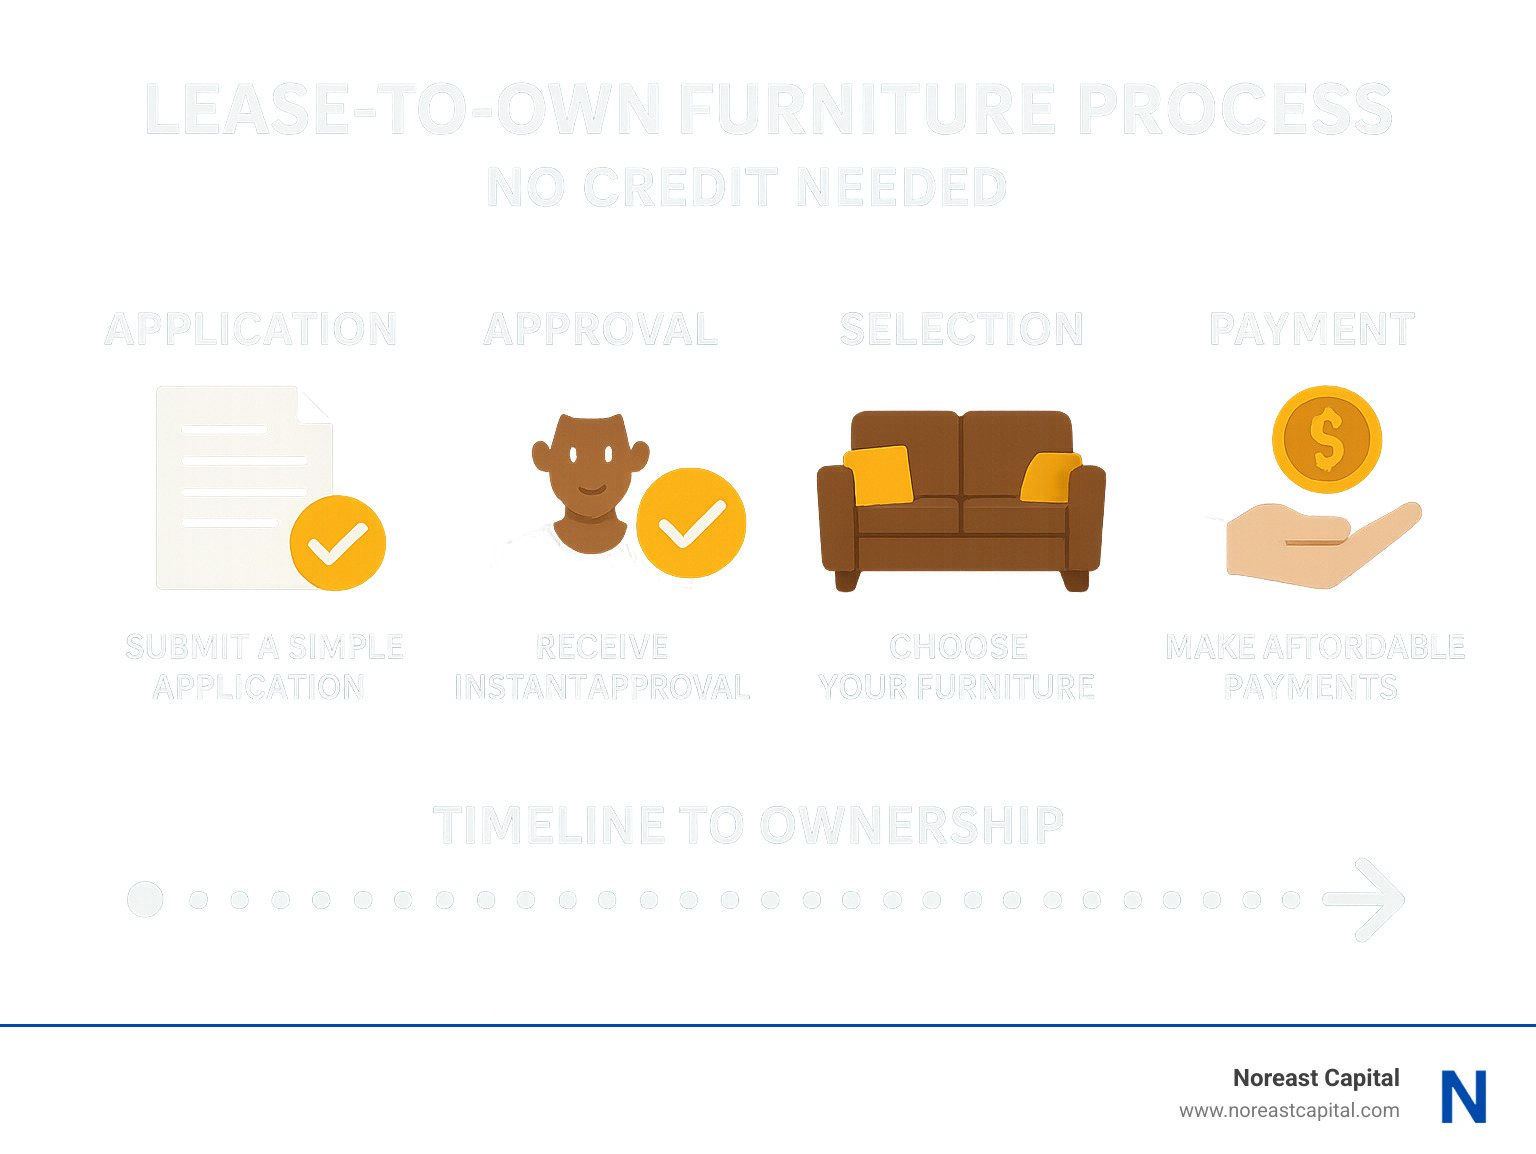
Think of lease-to-own as a stepping stone to ownership. Instead of focusing on your credit score, these programs look at your income stability and banking history. It’s refreshingly simple:
You apply (takes just minutes), get approved for a spending limit (often up to $5,000), pick out the furniture you love, make a small initial payment (typically just $10-$59), and take your furniture home that very day! You’ll make regular payments that fit your schedule—weekly, bi-weekly, or monthly—until you own the furniture outright, usually after about 12 months.
Behind the scenes, the leasing company actually purchases the furniture and leases it to you until all payments are complete. This clever structure is why they can say “yes” when traditional financing says “no.”
Most lease-to-own furniture agreements include early purchase options that can save you money. The popular 90-day option lets you pay off the furniture early at a significant discount—perfect timing for when you receive your tax refund or bonus!
As Julie from Salt Lake City shared: “I was able to furnish my entire living room through a lease-to-own program when no one else would approve me. The 90-day option helped me save money when I got my tax return.”
Lease to Own Financing No Credit Check
Lease-to-Own vs. Rent-to-Own
You might hear “lease-to-own” and “rent-to-own” used interchangeably at furniture stores, and while they’re similar, there are some subtle differences worth knowing.
With lease-to-own arrangements, you’ll typically commit to a fixed 12-month term with structured payment schedules. These often include that beneficial 90-day early purchase option I mentioned. Many providers also include service and repairs during your lease period—so if that recliner mechanism stops working, they’ve got you covered!
Rent-to-own programs might offer more flexibility in rental periods and sometimes allow you to return items with no further obligation if your situation changes. They commonly include perks like free delivery, setup, and ongoing service throughout the agreement.
For example, many leasing companies structure their agreements as 12-month leases with early purchase options, while others emphasize their no-hidden-fees approach with included delivery and service.
In practice, both options give you that same wonderful result: beautiful furniture now, with ownership after completing your payments.
Lease-to-Own vs. Traditional Financing
Choosing between lease-to-own and traditional financing? Here’s what makes them different:
When you use traditional financing, you own the furniture immediately but owe a debt that appears on your credit report. You’ll need a decent credit score to qualify, and you’ll pay interest on your purchase.
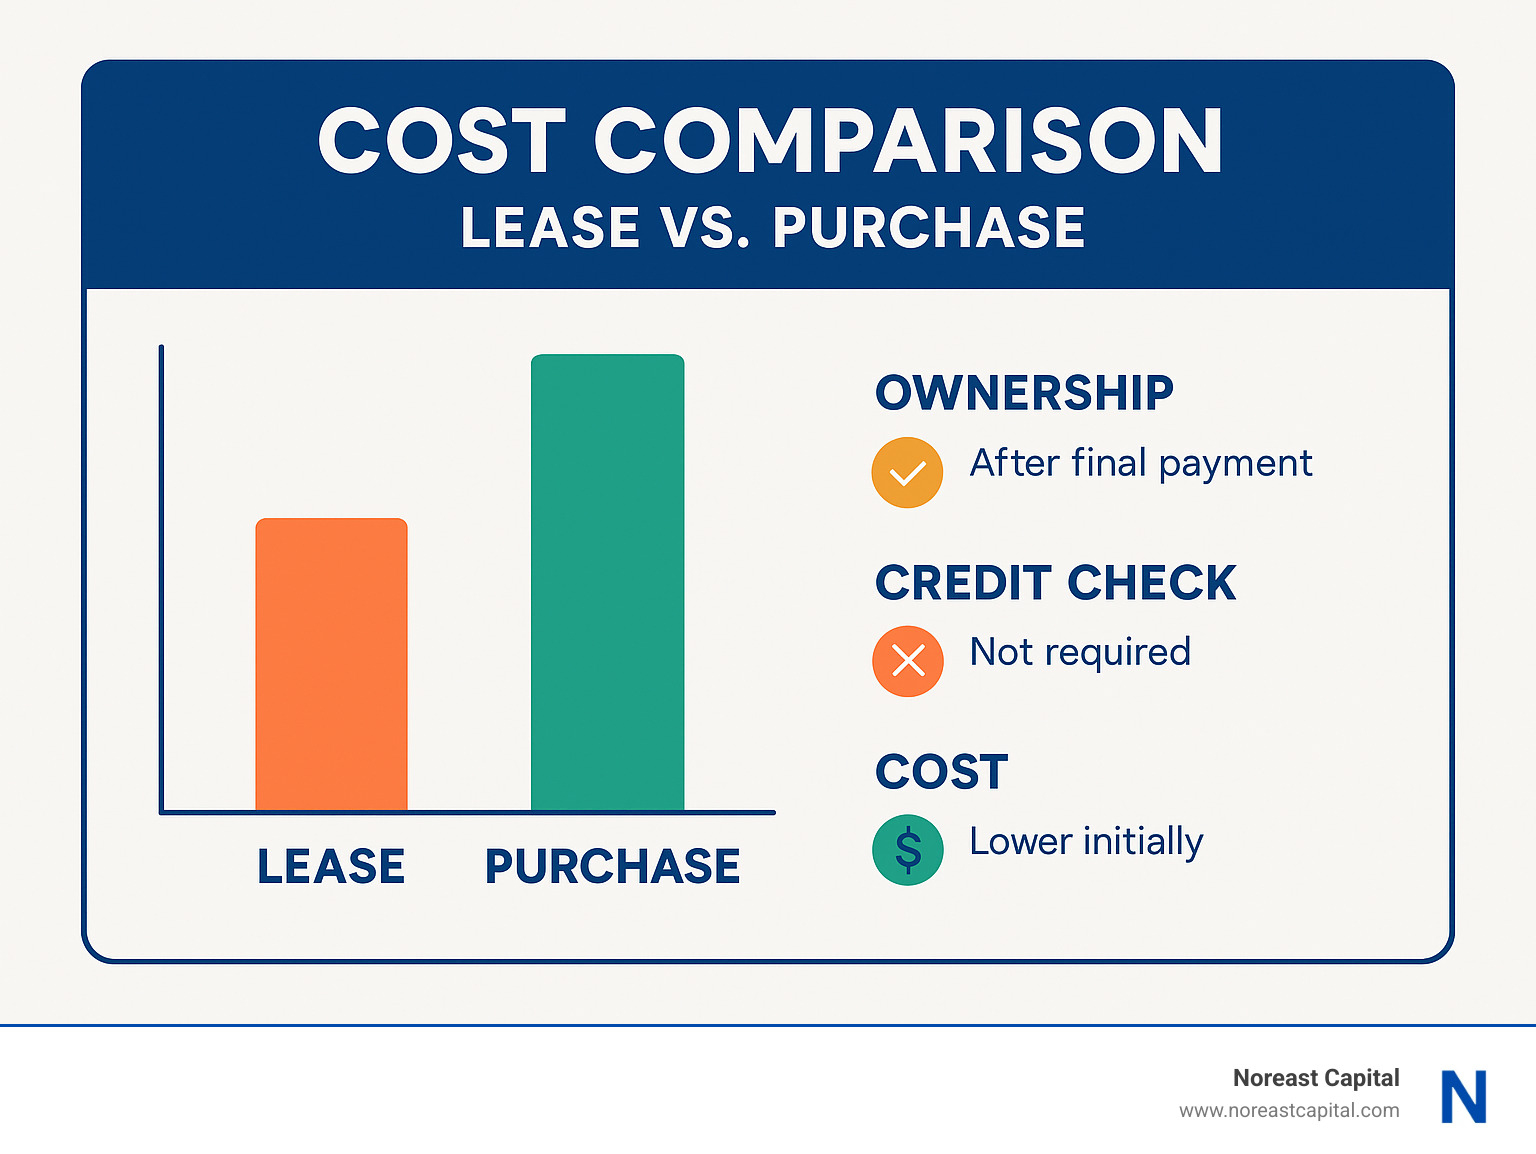
With no credit check lease-to-own furniture, the leasing company maintains ownership until your final payment. Your credit score doesn’t matter for approval, and these agreements typically don’t report to credit bureaus or increase your debt load. Instead of charging interest, there’s a markup over the cash price built into your payments.
As one happy customer explained: “After being denied for store credit cards, I was able to get the sectional sofa I needed through a lease-to-own program. I made bi-weekly payments that matched my paydays, and now I own it outright.”
The ownership path is different, but the destination is the same—furniture you love in a home you’re proud of!
Benefits, Drawbacks & Cost Comparison
When considering no credit check lease to own furniture, it helps to look at both sides of the coin. After all, this option has plenty of perks, but also some considerations worth knowing about before you sign on the dotted line.
Main Benefits
The beauty of no credit check lease to own furniture starts with its remarkably simple approval process. Unlike traditional financing that has you jumping through hoops, these programs look at your income and banking history rather than that pesky credit score. Most folks receive approval within minutes, and the approval rates soar much higher than traditional financing options.
Your wallet will thank you for the low upfront costs too. Initial payments can be as modest as $10 at some retailers, with no large down payment to drain your savings. Even better, most agreements include free delivery and setup – a nice touch when you’re already watching your pennies.
Flexibility is another major plus. You can choose payment schedules that align perfectly with your payday – weekly, bi-weekly, or monthly options make budgeting so much easier. And if life throws you a curveball, many providers allow you to adjust payment dates to match your changing circumstances.
The early purchase options might be my favorite feature. Those 90-day purchase options can save you substantial money compared to the full term. Many providers offer additional discount milestones too – many lease-to-own companies, for example, give generous discounts if you buy out at the 4-month mark.
Your credit score stays untouched since most providers don’t perform hard credit inquiries that could lower your score. They typically don’t report to credit bureaus either, so your debt-to-income ratio remains unchanged – a real blessing if you’re working on rebuilding credit.
Perhaps most appealing is the immediate gratification. You can take home your furniture the same day you’re approved – no waiting for credit approval or scheduling delivery weeks out. As Hank from Dallas shared: “I had a great experience from the start. The approval was quick, and I got to take my furniture home that day. I’ll definitely use this option again.”
Potential Drawbacks
While no credit check lease to own furniture offers tremendous accessibility, there’s no free lunch in this world. The total cost over time will be higher than the cash price – you’re paying a premium for the convenience and no-credit-check approval. For perspective, a sofa with a $1,000 cash price might end up costing $1,500-$1,800 over the full lease term.
Geography matters too. Due to varying state regulations, these programs aren’t available everywhere. Some leasing companies don’t operate in certain states like Minnesota, New Jersey, Wisconsin, or Wyoming. Worth checking availability before getting your heart set on this option.
Keep an eye out for potential fees that can add up. Late payment charges may apply if you miss a due date, and some providers tack on processing fees or optional services like loss-damage waivers that increase your total cost.
Your selection might be more limited than traditional shopping since you’re restricted to participating retailers. Not all furniture styles or high-end brands participate in lease-to-own programs, which might disappoint if you have specific tastes.
Ownership timeline too – you don’t actually own the furniture until you’ve made all your payments. Early termination typically means returning the items, and missing payments could result in repossession. Not ideal if you’ve grown attached to that comfy sectional!
Total Cost in Real Dollars
Let’s talk actual numbers to help you understand what you’re signing up for. Here’s a real-world example for a living room set with a retail cash price of $2,000:
| Payment Method | Initial Payment | Monthly Payment | Term | Total Cost | Premium Paid |
|---|---|---|---|---|---|
| Cash Purchase | $2,000 | $0 | Immediate | $2,000 | $0 |
| Credit Card (15% APR) | $0 | $186 | 12 months | $2,232 | $232 |
| Lease-to-Own (Full Term) | $59 | $195 | 12 months | $2,399 | $399 |
| Lease-to-Own (90-Day Purchase) | $59 | $195 | 3 months | $2,175 | $175 |
The numbers tell an interesting story – that 90-day early purchase option can dramatically reduce your premium compared to the full lease term. If you expect to have funds available within a few months (maybe from a tax refund or work bonus), this approach can be particularly smart.
As Derrek from Brooklyn noted in his review: “Thank you for giving AMAZING customer service! The 90-day option saved me hundreds compared to the full lease term.”
Taking advantage of these early purchase options means you get the immediate access you need while keeping the total cost much closer to traditional financing options. It’s like having your cake and eating it too – immediate furniture with reasonable costs if you plan accordingly.
Scientific research on consumer leasing
How to Qualify & Apply Fast
Getting approved for no credit check lease to own furniture is surprisingly simple and quick. If you’ve been turned down for traditional financing before, you’ll find this process refreshingly accessible.

Eligibility Checklist
The beauty of lease-to-own programs is their straightforward requirements. Unlike banks that seem to need your life story, these providers focus on stability rather than your financial past.
You’ll need to be at least 18 years old with a valid government-issued ID – this can be a driver’s license, state ID, or passport. If you don’t have a Social Security Number, many providers accept an ITIN (Individual Taxpayer Identification Number) instead.
Financial requirements are refreshingly simple too. You’ll need a steady income of at least $1,000 monthly and an active checking account that’s been open for at least 90 days. Most providers like to see at least 3 months at your current job to establish stability.
What’s noticeably absent? Credit checks. As one customer shared with me, “After years of credit rejections, I was shocked when I got approved in minutes for my new sectional sofa.”
Typical Requirements & Documents
When you sit down to apply, have your personal information ready. You’ll need your full legal name, date of birth, and contact details including your current address.
For the financial side, be prepared to share details about your income amount, pay frequency (whether you’re paid weekly, bi-weekly, or monthly), and your next payday date. Your employer information helps verify your income stability.
The most important financial details are your checking account number and bank routing number. These allow for automatic payments, which most providers require. You’ll also need a debit or credit card for your initial payment, which typically ranges from $10-$59.
What’s particularly nice is that most applications don’t require uploading documents for initial approval. The process is designed to be hassle-free, though occasionally some applicants receive “conditional approval” that might require a recent bank statement to verify income.
From Approval to Delivery
Here’s where things get exciting – the journey from application to having new furniture in your home happens remarkably fast:
Start by completing a simple application either online or in-store. Most take just 5-10 minutes, and the majority of applicants receive an instant decision. Once approved, you’ll know exactly how much you can spend.
Next, you’ll select furniture within your approved amount. Make your initial payment, and you’re ready to either pick up your items immediately or schedule delivery – which is often completely free. Many retailers offer same-day delivery and setup, so you could be enjoying your new furniture by evening.
Finally, you’ll confirm your payment schedule, ideally aligning it with your paydays for maximum convenience. Most providers offer flexible weekly, bi-weekly, or monthly payment options to fit your financial rhythm.
As Maria from Houston told us, “I applied at 10 AM on Saturday, was approved by 10:15, and had my new bedroom set delivered and set up by 3 PM the same day. I couldn’t believe how easy it was!”
The entire process eliminates the waiting and uncertainty that comes with traditional financing. You know immediately if you’re approved, for how much, and can get your furniture right away – no waiting for credit checks or delivery schedules.
Smart Money Tips & FAQs
Making the most of a no credit check lease to own furniture agreement isn’t just about getting approved—it’s about being smart with your payments and understanding how to save money along the way.

Top Money-Saving Tips
When I talk to customers about no credit check lease to own furniture, I always emphasize that aligning your payments with your paycheck is a game-changer. If you get paid bi-weekly, set up bi-weekly payments that hit your account when you’re flush with cash—not the day before payday when things might be tight.
The 90-day purchase option is your secret weapon for savings. Think of it this way: if you can pay off your furniture within the first three months, you’ll often save hundreds compared to the full 12-month term. I’ve seen customers save up to 40% by taking advantage of this option when they receive tax refunds or bonuses.
Keep your eyes peeled for “same as cash” promotions too. These golden opportunities let you pay the regular retail price with no markup if you complete payment during the promotional period—usually 90 to 180 days. It’s like getting all the benefits of no credit check lease to own furniture without the premium price.
Be wary of those tempting add-ons at checkout. That $14.99 monthly loss-damage waiver might seem small, but it adds up to nearly $180 over a year—money that could go toward early payoff instead. Unless you have rambunctious kids or pets that might damage the furniture, these extras rarely pay for themselves.
Before signing anything, take five minutes to read the agreement carefully. I know, paperwork isn’t fun, but understanding the early purchase formula and potential fees will save you headaches later. One customer told me she saved over $300 just by noticing she could buy out her living room set at the 4-month mark with a special 25% discount offered by her leasing company.
Creating a separate “furniture payment” category in your budget might seem obvious, but you’d be surprised how many folks forget to account for these payments when planning their monthly expenses. Even with auto-pay set up, make sure the money is there—overdraft fees can quickly erase any deals you worked hard to get.
Finally, always consider the total cost versus the cash price. Is paying $2,400 over time worth it for a $2,000 sofa set you need right now? For many families, the answer is yes—especially when the alternative is sitting on the floor for six months while saving up. But making this decision with your eyes wide open is key.
Frequently Asked Questions about No Credit Check Lease-to-Own Furniture
Is no credit check lease-to-own furniture right for me?
When clients ask me if no credit check lease to own furniture is right for them, I always say it depends on their unique situation. If you need that bedroom set today but don’t have $2,000 sitting in your account, this option makes perfect sense. It’s also ideal if traditional financing has given you the cold shoulder due to limited credit history.
I’ve worked with countless customers who love the flexibility of choosing payment schedules that match when they get paid. One client, a nurse who gets paid every other Friday, set up her payments for Fridays and never has to worry about having funds available.
That said, this option isn’t for everyone. If you have stellar credit that qualifies you for those sweet 0% store financing deals, you’ll likely save money going that route. And if you’re the ultra-patient type who can sleep on an air mattress for three months while saving for a bed, paying cash will always be cheaper in the long run.
The key is honest assessment—do you need the furniture now, can you make the payments comfortably, and is the convenience worth the additional cost? For most of my customers, the answer has been a resounding yes.
Does no credit check lease-to-own furniture affect my credit score?
Good news—most no credit check lease to own furniture programs won’t impact your credit score in any meaningful way. When you apply, companies typically perform what’s called a “soft inquiry” that doesn’t leave a mark on your credit report. This is a huge relief for folks who are trying to rebuild their credit and can’t afford more inquiries.
What surprises many customers is that these programs generally don’t report your payment history to credit bureaus either. This is a double-edged sword: your on-time payments won’t help build your credit score, but late payments won’t hurt it either (at least directly).
That said, there’s an important exception: if you stop making payments altogether and your account goes to collections, that collection activity could potentially appear on your credit report. I always advise customers to communicate with the leasing company if they’re facing payment difficulties—most are willing to work with you rather than send your account to collections.
As one customer told me after completing her lease: “I was worried it would hurt my credit, but my score actually went up during the lease period because I wasn’t taking on traditional debt.”
Can I return the furniture early without penalty?
One of the most flexible aspects of no credit check lease to own furniture is the return policy. Unlike traditional financing where you’re locked into payments until the loan is paid off, most lease-to-own programs let you return items with no further obligation if your circumstances change.
Let’s say you lease a dining set but then need to downsize to a smaller apartment where it won’t fit. Simply contact customer service, arrange a pickup (which is often free), and once the furniture is returned in reasonable condition, your payment obligations end. You only pay for the time you actually used the furniture.
I had a customer who leased a sectional sofa but got a job offer in another state three months later. She was relieved to find she could arrange a pickup, return the sofa, and walk away without any early termination fees or penalties. The process was as simple as making a phone call and scheduling a convenient pickup time.
Just remember that “good condition” means normal wear and tear—if your dog decided the sofa arm was a chew toy, you might face some additional charges. The definition of normal wear varies by company, so it’s worth clarifying this when you sign your agreement.
Conclusion & Next Steps
Furnishing your home shouldn’t depend on your credit score. No credit check lease to own furniture offers a practical solution when you need items now but don’t have perfect credit or the full purchase amount upfront.
Throughout this guide, we’ve explored how these programs can help you create a comfortable home on terms that work for your situation. The beauty of lease-to-own is its accessibility – approval based on income and banking history rather than credit scores means almost everyone has a path to quality furniture.
Remember the key advantages: quick approvals (usually within minutes), low initial payments ($10-$59 to start), and flexible payment schedules that can align perfectly with your payday cycle. While the total cost is higher than paying cash upfront, those smart 90-day early purchase options can significantly reduce what you’ll pay overall.
Before signing any agreement, take a moment to:
Compare several providers’ terms and conditions to find your best match. Each company has slightly different policies on early purchases, payment schedules, and delivery options. Understanding the total cost – both over the full term and with early purchase options – helps you budget effectively. And always read the fine print before signing to avoid any surprises down the road.
When you schedule your payments to match when you get paid, you’ll find it much easier to meet your obligations without stress. Many customers find the bi-weekly option works perfectly with their paycheck schedule.
At Noreast Capital, we understand that maintaining healthy cash flow while accessing the items you need is essential. Though our primary focus is commercial equipment financing in the Annapolis, Baltimore, and Washington DC areas, we recognize how important flexible financing solutions are for everyone.
No credit check lease to own furniture represents more than just a transaction – it’s about creating a comfortable home on your terms, regardless of your credit history. It’s about dignity and access when traditional financing says “no.”
For more information about no-credit leasing options and to explore solutions that might work for your unique situation, visit our resource page at More info about no-credit leasing options.
With the right approach and understanding, you can make lease-to-own work beautifully for your home and budget. After all, everyone deserves a comfortable place to call home.