

Tractor financing is a pivotal solution for farmers and agricultural businesses looking to acquire essential machinery without the hefty upfront costs. It allows you to spread out payments over time, alleviating the immediate financial burden and helping maintain cash flow. Whether you’re aiming to purchase new or used tractors, finance options offer flexibility custom to your needs.
Here’s a quick overview of what tractor financing can offer you:
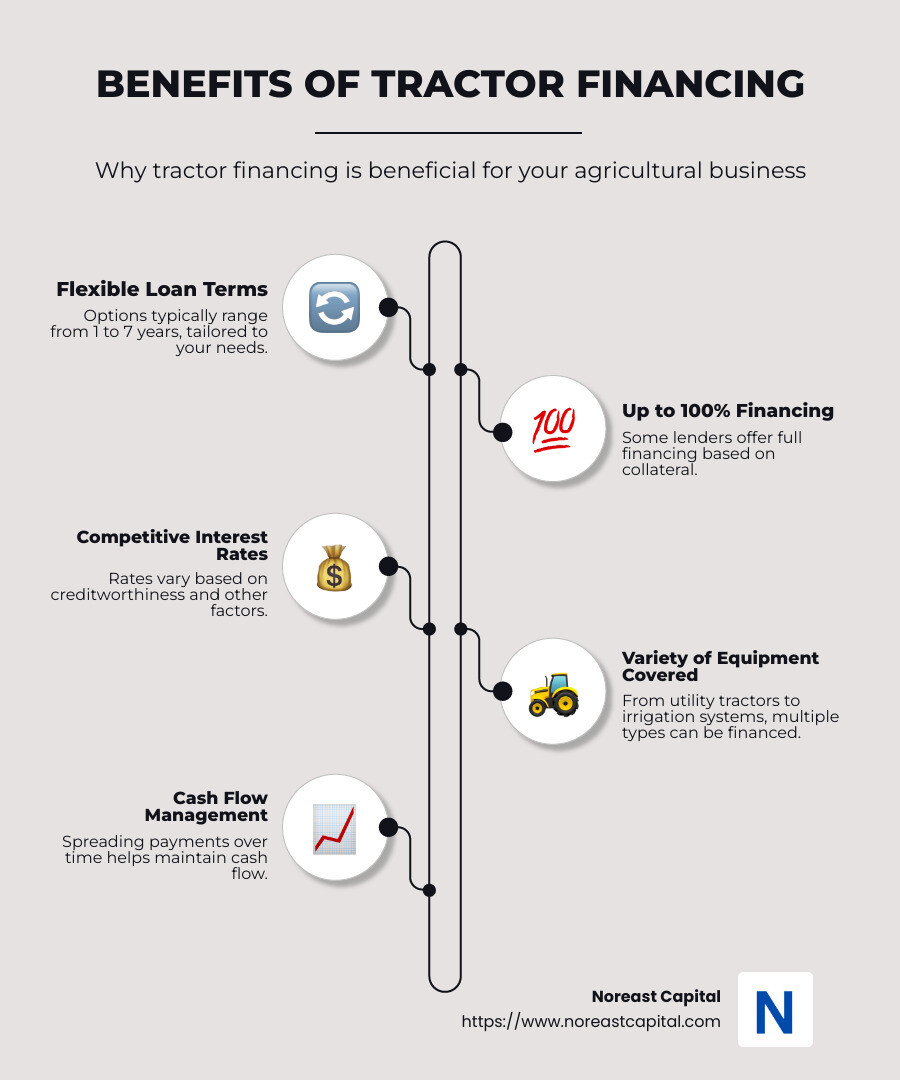
- Flexible loan terms: Options typically range from 1 to 7 years, depending on your needs.
- Up to 100% financing: Some lenders offer full financing based on collateral.
- Competitive interest rates: Rates vary based on creditworthiness and other factors.
- Variety of equipment covered: From utility tractors to irrigation systems, various types of equipment can be financed.
I’m Vincent Cerniglia, a seasoned expert in tractor financing with experience in providing nationwide finance and leasing solutions. With years of expertise, I can guide you through the nuances of equipment financing to help you make informed decisions for your business.
Understanding Tractor Financing
Navigating tractor financing can seem complex, but understanding the key elements can simplify the process. Let’s break down what you need to know about credit score requirements, loan terms, and collateral.
Credit Score Requirements
Your credit score is a critical factor in securing tractor financing. Lenders use it to assess your reliability as a borrower. Generally, a higher credit score can help you secure better interest rates and terms. For instance, some financing offers require a minimum credit score of 640 to qualify for competitive rates. A good credit score signals to lenders that you’re a low-risk borrower, which can open doors to more favorable loan conditions.
Loan Terms
Loan terms for tractor financing can vary significantly. Typically, terms range from 2 to 7 years, giving you flexibility to choose a repayment plan that fits your financial situation. Shorter terms might come with higher monthly payments but can save you money on interest over time. Conversely, longer terms can lower your monthly payments, making it easier to manage cash flow, but may cost more in interest.
Collateral
Collateral is often required when financing a tractor. This means the tractor itself or other assets may be used as security for the loan. Offering collateral can sometimes help you secure better loan terms or interest rates. However, if you default on the loan, the lender may take possession of the collateral.
Understanding these elements can help you make informed decisions when considering tractor financing. In the next section, we’ll dive deeper into the different types of tractor loans available and how they can benefit you.
Types of Tractor Loans
When it comes to tractor financing, there are a few main types of loans to consider. Each has its own benefits and structures, so understanding them will help you choose the best option for your needs.
Equipment Loans
Equipment loans are specifically designed for purchasing tractors and other machinery. These loans typically use the equipment itself as collateral, which can make them easier to obtain if you have a solid credit history. One of the advantages of equipment loans is that they often cover up to 100% of the purchase price, as seen with financing options from Southern AgCredit. This means you might not need a hefty down payment upfront.
Repayment terms for equipment loans can range from 1 to 7 years, depending on factors like the condition and age of the tractor. These loans are a popular choice because they allow you to own the equipment outright once the loan is paid off.
Conventional Loans
Conventional loans are another option for financing a tractor. Unlike equipment loans, these are not specifically custom to machinery purchases. However, they can still be a viable option if you’re looking for flexibility or have other financing needs. Conventional loans might come with different interest rates and terms, often influenced by your credit score and financial history.
Repayment terms for conventional loans can vary widely. They might offer more flexibility in terms of how you structure your payments, but they often require a higher credit score and more robust financial documentation.
Repayment Terms
Understanding repayment terms is crucial when choosing a loan. The terms dictate how long you’ll be paying off the loan and can impact your monthly payments.
Short-term loans (1-3 years) often have higher monthly payments but lower overall interest costs.
Long-term loans (4-7 years) can ease monthly financial burdens but might result in paying more interest over time.
It’s important to weigh your current cash flow against the total cost of the loan to find a balance that works for you.
By understanding the types of loans available and their repayment terms, you can make a more informed decision about tractor financing. In the next section, we’ll explore the benefits of financing a tractor and how it can support your farming operations.
Benefits of Tractor Financing
Financing a tractor offers several advantages that can make managing your farm’s finances easier and more efficient. Here’s how tractor financing can benefit your operations:
Cash Flow Management
One of the biggest benefits of financing is improved cash flow management. Instead of paying a large sum upfront, you can spread the cost over time with manageable monthly payments. This approach helps you keep more cash on hand for other essential expenses like seeds, fertilizers, and labor.
For instance, using tractor financing can free up funds for unexpected repairs or investment opportunities. This flexibility is crucial in the farming business, where costs can be unpredictable.
Flexible Terms
Tractor financing often comes with flexible terms that can be custom to your needs. You can choose the length of the loan based on your cash flow and financial goals. Whether you prefer short-term loans with higher payments or long-term loans with lower payments, there’s an option that can fit your budget.
Many lenders allow you to customize your payment schedule, which can be particularly useful if your income varies seasonally. This flexibility can help you align payments with your revenue cycles.
Tax Benefits
Financing your tractor can also present tax benefits. Under certain conditions, you may be able to deduct the interest paid on your loan, which can reduce your taxable income. Additionally, you might qualify for deductions like the Section 179 Deduction, which allows you to write off the full purchase price of qualifying equipment in the year of purchase.
This deduction can lead to significant tax savings, making it a smart financial move for many farmers. For example, if you finance a $50,000 tractor and qualify for the deduction, you could potentially save thousands in taxes.
By understanding these benefits, you can see how tractor financing can support your farming operations, improve your cash flow, and provide financial flexibility. In the next section, we’ll answer some frequently asked questions about tractor financing to further guide you in making the right decision for your farm.
Frequently Asked Questions about Tractor Financing
What credit score is needed to finance a tractor?
When it comes to tractor financing, your credit score plays a crucial role. Lenders use it to assess your reliability as a borrower. Generally, a higher credit score can help you secure better interest rates and terms. Most lenders look for a score of at least 650, but requirements can vary.
For example, some specialized agricultural lenders may consider scores as low as 600, especially if you have strong collateral or a solid business plan.
How long do you finance a tractor for?
The length of time you can finance a tractor varies based on the lender and the type of loan. Typical loan terms range from 2 to 7 years. Choosing the right term depends on your financial situation and cash flow needs.
Shorter terms often mean higher monthly payments but can save you on interest. Longer terms may offer lower payments, which can be helpful if you need to manage cash flow over a longer period.
What is the best type of loan for a tractor?
The best type of loan for a tractor depends on your specific needs. Equipment loans are a popular choice as they are designed specifically for purchasing machinery. These loans often come with competitive rates and flexible repayment options.
Collateral is usually required, which means the tractor itself serves as security for the loan. This reduces the lender’s risk and can lead to better terms for you.
If you’re unsure which loan type is best, consider consulting with a financial advisor or a trusted lender to explore your options.
In the next section, we’ll explore more about how Noreast Capital can help you steer these options and find the best financing solution for your agricultural needs.
Conclusion
At Noreast Capital, we understand that managing your cash flow is vital for your business’s success. That’s why we offer equipment leasing solutions that allow you to use the equipment you need without the burden of ownership.
Leasing your tractor through us means you can keep your cash flow healthy. Instead of a large upfront payment, you make manageable monthly payments. This way, you can invest your capital in other areas of your business.
Our leasing options come with flexible terms designed to fit your unique needs. Whether you need a short-term lease or a longer arrangement, we have a solution that works for you.
By choosing Noreast Capital, you’re not just leasing equipment; you’re gaining a partner committed to helping your business thrive. We provide guidance throughout the leasing process, ensuring you make informed decisions that benefit your operation.
In conclusion, tractor financing through leasing is a smart choice for managing cash flow and accessing the equipment you need. Trust us to support your business with our expertise and custom financial solutions.
To learn more about how we can help your business grow, visit our website or contact us directly. We’re here to assist you every step of the way.