Why Tractor Trailer Financing is Crucial for Your Business
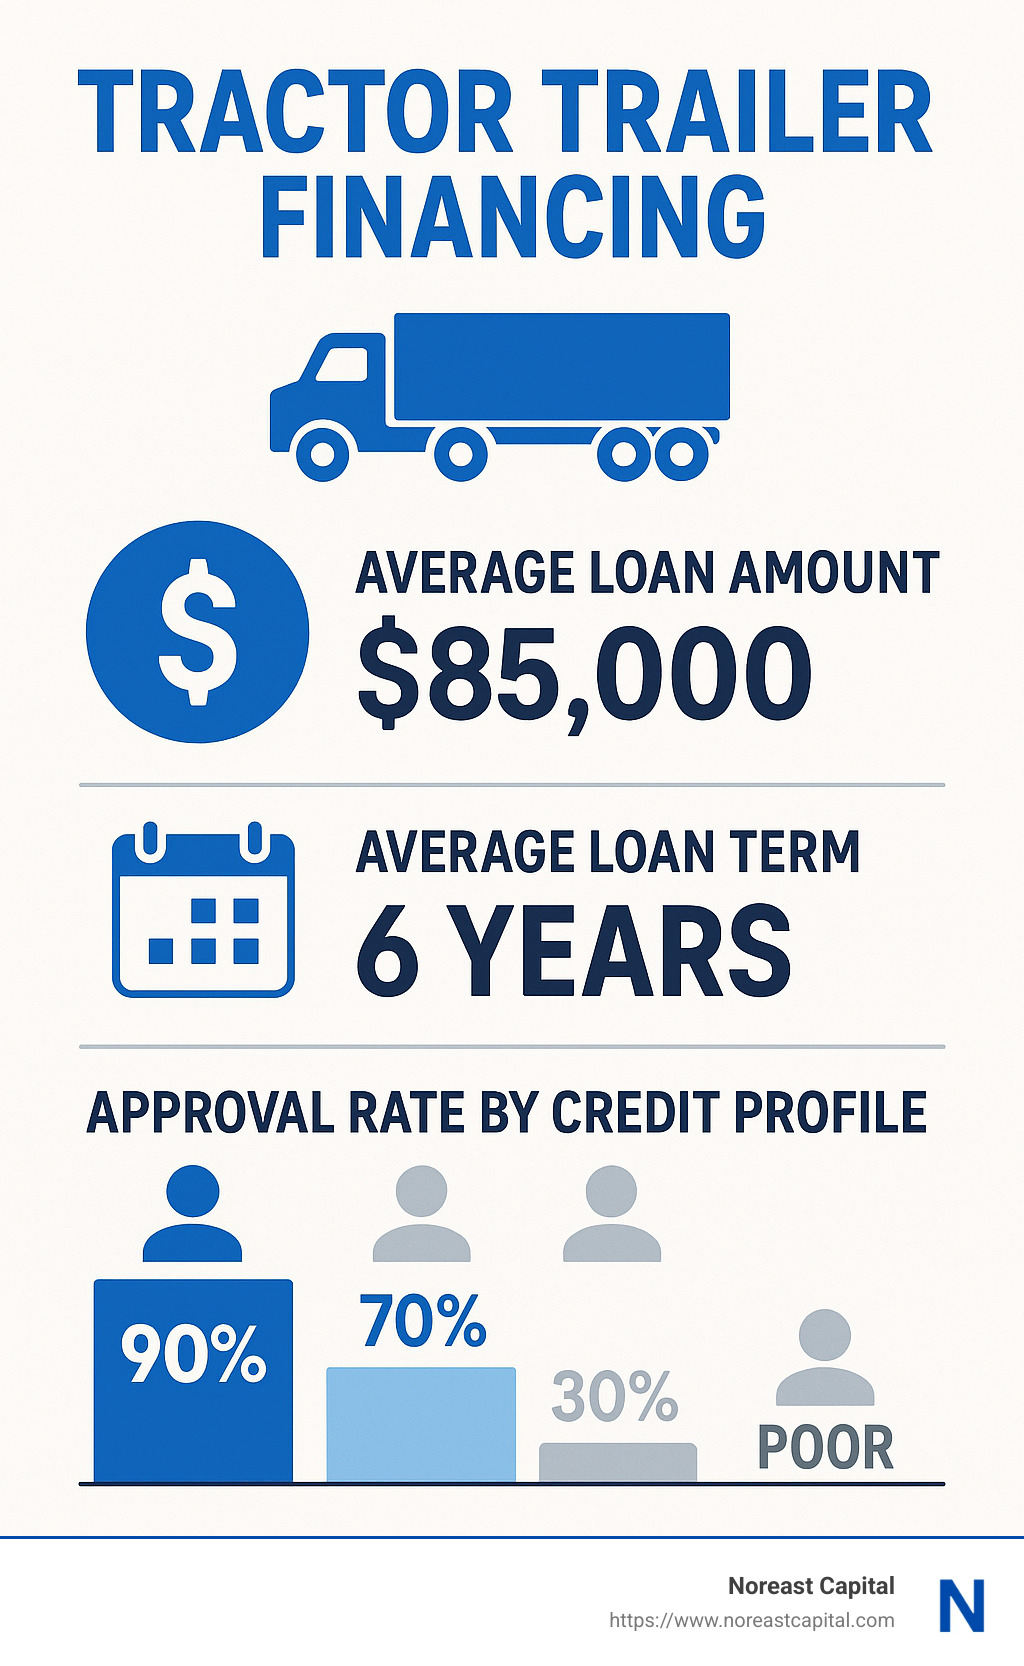
Tractor trailer financing is a specialized type of loan or leasing agreement designed for businesses to affordably acquire commercial trucks without large upfront costs.
Here’s what you need to know in a nutshell:
- Common Financing Options: Loans, leases, rent-to-own, dealer financing
- Interest Rates: Typically range from 5% to 36% APR, depending on creditworthiness
- Down Payments: Usually between 10% to 20%, but as low as 0% with excellent credit
- Term Lengths: Generally 24 to 72 months
- Credit Score Impact: Scores of 640+ may qualify for favorable rates, while scores as low as 500 might still qualify at higher rates
Choosing the right tractor trailer financing can be the difference between a thriving small business and strained cash flow. This guide will cover everything you need to understand about tractor trailer financing—making sure you can weigh your options and pick the right solution that keeps your business moving forward.
My name is Vincent Cerniglia, and I’m a financing expert with Noreast Capital Corporation, specializing in tractor trailer financing. Over the years, I’ve helped businesses of all sizes secure flexible, cost-effective financing solutions custom to their equipment needs.
Handy tractor trailer financing terms:
– tractor financing options
– bank loan for tractor
– used tractor financing
Types of Tractor Trailer Financing Options
When you’re ready to add a tractor trailer to your fleet, understanding the different tractor trailer financing options can make a huge difference to your business’s bottom line. The good news? You’ve got choices, each designed to meet specific business needs. Let’s explore these options to help you make the best decision for your financial health.

Understanding Tractor Trailer Financing Loans
Traditional loans are one of the most common ways businesses finance tractor trailers. With this type of tractor trailer financing, you borrow a lump sum from a lender to buy your truck upfront. The vehicle itself acts as collateral—which basically means the lender can take it back if payments aren’t made. (Don’t worry, we’re confident you’ll make those payments!)
Loan amounts can range widely—from $20,000 for single trucks up to $1,000,000 or more for entire fleets. Interest rates typically start around 5% for those with excellent credit and can reach as high as 36% if your credit score is lower. Terms are usually between 24 to 72 months, sometimes even stretching to 84 months to keep payments manageable.
One major benefit? Once your loan is paid off, you own the tractor trailer outright. Every payment you make builds equity in your asset, making it a smart investment for the long haul.
John, one of our clients from Baltimore, recently financed his Peterbilt through Noreast Capital. “I put down 15%, got a manageable 60-month loan at 7.5% interest, and now I’m building equity month after month,” he told us. “Plus, my accountant loves that the interest payments are tax-deductible!”
Leasing vs Buying Tractor Trailers
Not sure if you want to commit to ownership? Leasing provides a flexible alternative. Unlike traditional loans, leases let you use the tractor trailer for a set period without becoming the outright owner. This often means lower monthly payments, lower or no down payments, and more flexibility to upgrade later on.
At Noreast Capital, equipment leasing is one of our specialties. Leasing arrangements usually feature lower upfront costs and manageable monthly payments, helping you maintain your cash flow and business savings. Plus, lease payments can often be fully deductible as business expenses, offering helpful tax advantages.
Here’s a quick comparison for clarity:
| Aspect | Leasing | Buying |
|---|---|---|
| Initial Cost | Lower initial cost, minimal or zero down payment | Higher upfront cost, typically 10-20% down payment |
| Monthly Payments | Usually lower monthly payments | Typically higher payments |
| Ownership | No ownership unless lease-to-own option selected | Full ownership after loan repaid |
| Tax Benefits | Payments often fully deductible as business expenses | Depreciation deductions plus interest expense deductions |
| Equipment Upgrades | Easy upgrade at end of lease | Sell or trade-in required for upgrades |
| Maintenance Costs | May be covered in lease agreement | Fully your responsibility |
| End of Term | Option to return, renew, or purchase equipment | You own it outright |
Industry data shows that about 80% of businesses prefer leasing or financing equipment instead of buying outright—and it’s easy to see why. Leasing gives you flexibility, preserves cash flow, and can help manage maintenance costs.
One of our clients, Maria from Jersey City, sums it up nicely: “Leasing through Noreast Capital was perfect for me. I didn’t have a huge down payment, and I like knowing I can upgrade easily when the lease ends. Plus, maintenance is included, so less hassle overall!”
Rent-to-Own and Dealer Financing
If you’re looking for something between leasing and traditional loans, rent-to-own and dealer financing can be smart choices.
With rent-to-own, your payments work toward eventual ownership. It offers flexibility: you can return the tractor trailer if you no longer need it, or choose to buy it once you’ve made all your payments. This is great if you’re just getting started, have lower credit scores, or prefer less initial risk.
Dealer financing is another convenient option, provided directly at the truck dealership. Major manufacturers like Volvo, Peterbilt, and Freightliner often provide competitive financing deals and special incentives right at the point of sale. This option can simplify your buying process and offer custom payment plans aligned with your business cycles.
However, it’s important to watch for potential downsides. Rent-to-own plans can sometimes cost more overall, and dealer financing might limit your negotiating power on truck price.
One of our fleet-operating clients from Washington, DC initially liked the ease of dealer financing but chose Noreast Capital instead. “The dealership offered convenience, sure—but Noreast Capital gave us better rates, more flexibility, and financing terms that matched our seasonal income fluctuations perfectly,” he shared.
If you’re curious about other financing possibilities, check out some additional resources from Noreast Capital:
The bottom line? Choosing the right type of tractor trailer financing depends on your unique business needs, financial situation, and goals. Whether it’s owning outright, leasing for flexibility, or a mixture of both—Noreast Capital has you covered.
Eligibility Requirements and Credit Considerations
Understanding what lenders look for when approving tractor trailer financing applications can significantly improve your chances of securing favorable terms. While requirements vary between lenders, certain factors consistently influence the approval process.

Credit Scores and Tractor Trailer Financing
Your credit score plays a pivotal role in determining not only whether you qualify for financing but also what interest rates and terms you’ll receive. Based on our experience at Noreast Capital and industry standards, here’s how credit scores typically impact tractor trailer financing:
- Excellent (720+): Access to the best interest rates (as low as 5-7%), higher approval amounts, minimal down payment requirements (potentially 0% down), and the most flexible terms
- Good (660-719): Competitive rates, standard down payment requirements (10-15%), and solid approval odds
- Fair (620-659): Higher interest rates, larger down payment requirements (15-20%), and potentially shorter loan terms
- Poor (580-619): Significantly higher rates, substantial down payments (20-30%), and stricter terms
- Very Poor (Below 580): May require specialized lenders, extremely high interest rates, large down payments (30%+), or additional collateral
“While many lenders prefer a score of at least 640, some will consider scores as low as 500, typically with higher interest rates and down payment requirements,” notes a recent industry report.
For those with challenged credit, there are still options. Specialized lenders focus on working with borrowers with less-than-perfect credit, even if you have had bankruptcy in the past, by making more flexible lending decisions.
At Noreast Capital, we take a holistic approach to credit evaluation. While your credit score is important, we also consider:
- Time in business
- Revenue stability
- Industry experience
- Value of the equipment being financed
- Strength of your business plan
If your credit score isn’t ideal, consider these strategies to improve your financing prospects:
- Provide a larger down payment to offset perceived risk
- Secure a co-signer with stronger credit
- Demonstrate strong cash flow through bank statements
- Build a relationship with the lender before applying
- Consider lease options which sometimes have less stringent credit requirements
Preparing Required Documents
Being properly prepared with the right documentation can streamline your tractor trailer financing application process and demonstrate your business’s credibility to lenders.
Based on our experience at Noreast Capital, here’s a comprehensive list of documents typically required for tractor trailer financing applications:
Business Documentation:
– Business license and registration
– Articles of incorporation or organization (for corporations or LLCs)
– EIN (Employer Identification Number) documentation
– Business bank statements (typically the last 3-6 months)
– Profit and loss statements
– Balance sheets
– Business tax returns (last 2-3 years)
Personal Documentation:
– Personal identification (driver’s license, passport)
– Personal tax returns (last 2-3 years)
– Personal bank statements
– Personal financial statement
– CDL (Commercial Driver’s License) if applicable
Equipment Documentation:
– Detailed description of the tractor trailer (year, make, model)
– VIN number
– Purchase agreement or invoice
– Vendor/dealer information
– Insurance information
Additional Documentation:
– Business plan (especially important for newer businesses)
– Driving record (for owner-operators)
– List of references (business and/or financial)
– Existing contracts or customer agreements (to demonstrate revenue potential)
“The process can take up to five business days once all required documentation is provided,” notes one lender’s FAQ section. Having your documents organized and ready can significantly expedite this timeline.
A client of ours who operates out of Annapolis shared this tip: “I created a dedicated digital folder with all my financing documents before I even started shopping for my trailer. When I found the right one, I was able to submit my complete application package to Noreast Capital the same day, which helped me secure the equipment before my competitor could.”
At Noreast Capital, we’ve streamlined our documentation requirements to make the process as efficient as possible while still conducting proper due diligence. We’re always available to help clarify exactly what you’ll need for your specific situation.
The Application Process for Tractor Trailer Financing
Navigating the application process for tractor trailer financing might seem intimidating at first glance—but don’t worry! Understanding each step involved can help you confidently approach lenders, minimize any hiccups, and ultimately secure financing terms that work best for your business.
Steps to Apply for Tractor Trailer Financing
The journey to financing your tractor trailer typically begins with an informal step: pre-approval or pre-qualification. Think of this as the “window-shopping” stage. At this point, lenders like us at Noreast Capital review basic business and personal information and perform a soft credit pull (don’t worry—this won’t affect your credit score!). This step helps you understand your borrowing power, potential interest rates, and estimated monthly payments. Getting pre-approved puts you in a stronger position when negotiating with dealers and ensures you don’t spend time looking at equipment beyond your budget.
With your pre-approval in hand, the next step is finding the perfect tractor trailer. Be mindful to consider whether you want new or used equipment, the make and model that fits your business needs, dealer reputation, warranty coverage, and maintenance history—especially important for used trailers. Take your time during this phase; it’s important to pick equipment that matches your operational demands without stretching your finances.
Once you’ve found the right tractor trailer, you’ll move into the formal application submission. This step involves filling out a detailed financing application and providing the required documentation—things like bank statements, tax returns, and information specific to your chosen equipment. At Noreast Capital, we’ve streamlined this process to make it as easy and stress-free as possible. We’ll walk you through exactly what’s needed, so there are no surprises.
Next comes the underwriting process—which is basically where the lender does its homework. During this stage, your lender verifies all your submitted information, performs a detailed credit check, evaluates the value and condition of the tractor trailer, and closely examines your business’s cash flow to ensure you’re able to comfortably repay the loan. Underwriting may feel a bit nerve-wracking, but it ensures that both you and the lender are protected from taking on more risk than necessary.
When underwriting is complete and everything checks out, you’ll receive your approval and financing documents. This paperwork clearly specifies crucial details like the approved financing amount, your interest rate, monthly payments, length of the term, and any additional fees or conditions. Before signing, take a deep breath, grab a cup of coffee, and carefully review every detail. If anything seems unclear, don’t hesitate to ask—at Noreast Capital, we’re always happy to clarify terms and make sure you’re fully comfortable before moving forward.
After signing your agreement, you’re ready for funding and equipment acquisition—the exciting part! Typically, the lender pays the dealership or seller directly, and once you’ve made any required down payment, you can take possession of your new tractor trailer. From here, you’ll follow a straightforward repayment schedule as outlined in your agreement. At Noreast Capital, many of our customers are pleasantly surprised at how quickly this entire process unfolds. One customer, Michael from Baltimore, shared: “From submitting my application to driving my new Freightliner, it took only seven business days!”
Even after the keys are in your hand, good lenders will provide ongoing post-funding support, helping you set up automatic payments, answering any questions, and keeping you informed on your account status. At Noreast Capital, we pride ourselves on maintaining relationships long after the paperwork is signed—we’re here to help at every stage.
Avoiding Common Pitfalls in Financing
To help ensure a smooth ride, it’s important to steer clear of common tractor trailer financing mistakes. One major pitfall we see frequently is businesses overestimating their budget. Committing to payments that strain your cash flow can create stress down the road. To avoid this, carefully evaluate your debt service coverage ratio (DSCR)—simply put, make sure the income from your business comfortably covers your monthly payments. Don’t forget to factor in additional expenses like insurance, fuel, and regular maintenance. Use helpful tools like our Tractor Financing Calculator to stay realistic about your budget.
Another common mistake is ignoring the fine print. Financial agreements often contain details like balloon payments, prepayment penalties, variable interest rates, or hidden fees that can affect you in the long run. Be sure to carefully read your agreement, and again—don’t be shy about asking questions if something is unclear. At Noreast Capital, transparency is core to our approach, and we make sure every client understands exactly what they’re signing up for.
It might feel tempting to jump right into shopping without first getting pre-approved, but trust us—skipping pre-approval can cost you. Without knowing your financing options up front, you may waste time looking at equipment that’s beyond your means or get stuck with unfavorable dealer financing terms. Pre-approval not only helps you shop confidently but also minimizes unnecessary credit inquiries, protecting your credit score.
Additionally, avoid the temptation of focusing only on monthly payments. While a low monthly payment sounds attractive, it doesn’t always mean you’re getting the best deal. Consider the total cost of financing over time, the actual interest rates, and how quickly you’ll build equity in your equipment. Align your payment structure with your business’s cash flow cycles, so you avoid financial stress at peak payment times.
Finally, don’t simply accept the first financing offer you see—neglecting to compare multiple offers can cost you big-time. Take the time to compare different lenders’ terms, rates, and fees to ensure you’re getting the best possible deal. One of our clients in Washington, DC shared how he almost chose dealer financing until he compared it against our terms at Noreast Capital: “I found out I could save over $12,000 over the life of my loan by going with Noreast Capital instead. I’m glad I took the extra time to compare!”
By understanding each step of the tractor trailer financing journey and avoiding these common pitfalls, you can confidently approach this process and secure financing that truly supports your business’s success. At Noreast Capital, we’re always here to guide you through every step, ensuring you find financing that moves your business forward.
Tips for First-Time Buyers
Buying your first tractor trailer is an exciting step toward building your trucking business. But as a first-time buyer, getting approved for tractor trailer financing might feel intimidating. Don’t worry—there are several ways you can strengthen your application, secure great financing terms, and start your journey off on the right foot.

Preparing as a First-Time Buyer
The key to successful tractor trailer financing as a first-time buyer is preparation. Showing lenders that you’ve thoroughly planned your trucking business will go a long way toward approval.
Start by creating a comprehensive business plan. Your business plan doesn’t have to be fancy or overly complicated, but it should clearly lay out your goals, revenue projections, and operating strategy. Explain your intended market, the type of customers you plan to serve, and how you’ll manage costs. At Noreast Capital, we’ve seen first-hand how lenders appreciate a clear, realistic plan that demonstrates thoughtful preparation.
Next, highlight your industry experience. Even if you’ve never owned a truck before, you might have valuable experience as a commercial driver, dispatcher, or transportation manager. Perhaps you’ve worked closely with trucking businesses in another capacity. Don’t underestimate this experience—make sure to emphasize it clearly in your application.
Another powerful way to improve your approval chances is to secure a substantial down payment. A larger down payment, typically around 20-25%, reassures lenders that you’re financially committed and reduces their risk. While saving up that much can feel daunting, remember you can tap into personal savings, sell unused assets, or even delay the purchase slightly while building your cash reserves.
If you’re having trouble getting approved independently, consider using a co-signer or co-borrower. A co-borrower will share equal responsibility on the loan and appear on the title, while a co-signer agrees to step in only if you default. Either option provides the lender with extra reassurance, particularly if the co-signer or co-borrower has strong credit or trucking industry experience.
Choosing the right equipment is also key. As tempting as it might be to start with a flashy new truck, a high-quality, well-maintained used tractor trailer often makes better financial sense. Used equipment is more affordable, easier to qualify for, and can help you build equity faster. Mark, one of our first-time clients from Maryland, initially dreamed of a brand-new rig—but after discussing his options at Noreast Capital, he chose a reliable three-year-old Volvo instead. He got approved faster, had lower monthly payments, and successfully launched his business.
Finally, make sure you have all necessary certifications and licenses in place. While not every lender explicitly requires a Commercial Driver’s License (CDL) or Motor Carrier (MC) Authority certification, having these in advance demonstrates your seriousness and readiness to operate responsibly.
For more resources and expert guidance, you can explore our detailed Farm Tractor Financing page designed especially for newcomers navigating equipment financing.
Utilizing Financing Calculators
Financing calculators are your best friend when preparing for your first tractor trailer purchase. These helpful tools let you play around with numbers to find financing scenarios that fit comfortably within your budget and business goals.
Our easy-to-use Tractor Financing Calculator at Noreast Capital lets you quickly see how different purchase prices, down payments, term lengths, and interest rates impact your monthly payment. You can also clearly visualize how much interest you’ll pay over the life of the loan.
Using a financing calculator early in your planning process can help you figure out exactly what you can afford without stretching your business finances too thin. Adjust the down payment or term length until you find the sweet spot—where your monthly payments feel manageable, yet you’re still building equity quickly.
Calculators also make comparing different scenarios fast and easy. Wondering whether to go with a 48-month or 60-month term? Curious how much you’d save if your credit score improved and you qualified for a lower interest rate? Just plug the numbers into the calculator and find the option that’s best for you.
When you’re ready to negotiate financing terms with dealers and lenders, having clear numbers from a financing calculator gives you confidence and bargaining leverage. You’ll know exactly what terms you need to make the deal work for your business.
One of our clients who recently financed with us shared how valuable this approach was: “Running different scenarios through Noreast Capital’s calculator showed me that a 15% down payment on a 48-month term gave me the best balance between affordable monthly payments and total cost. Having this knowledge ahead of time helped me secure the exact financing terms I needed.”
Taking these simple but strategic steps to prepare can make the tractor trailer financing process smooth and stress-free, even as a first-time buyer. At Noreast Capital, we’re always here to help you steer and succeed—so don’t hesitate to reach out with your questions.
Frequently Asked Questions about Tractor Trailer Financing
Can I get tractor trailer financing with bad credit?
Absolutely! Having bad credit doesn’t automatically disqualify you from securing tractor trailer financing, though it does usually mean you’ll face less favorable terms. Typically, you’ll encounter higher interest rates, ranging anywhere from around 15% up to 36% APR, and you’ll likely need a larger down payment—often between 20% to 30% or more. You may also see shorter financing terms and stricter documentation requirements.
But don’t worry—there are specialized lenders out there who can help borrowers with challenged credit histories. They may consider more than just your credit score, taking into account your overall business health and future potential.
At Noreast Capital, we also take a broader view of your business. Rather than focusing solely on your credit score, we look at the strength of your cash flow, your industry experience, time in business, the specific equipment you’re financing, and your customer relationships. If you’ve had past credit issues, be upfront about them and show evidence of recent financial improvement. Providing a stronger down payment, selecting a quality used truck rather than a brand-new one, finding a co-signer with better credit, or demonstrating consistent revenue can all improve your chances of securing financing.
One of our clients, who had a 540 credit score following a previous business bankruptcy, successfully secured financing by offering a 25% down payment and providing proof of steady revenue growth over the previous six months. It’s definitely achievable!
Is a down payment always required for tractor trailer financing?
Most of the time, yes—a down payment is usually required for tractor trailer financing. Typically, lenders ask for about 10-15% down from borrowers with excellent credit, 15-20% for those with good credit, and around 20-30% for fair or challenged credit scores.
However, there are exceptions. Some lenders offer zero-down or low-down-payment financing for businesses with exceptionally strong credit profiles or well-established financial histories. However, typically, these options require excellent credit.
At Noreast Capital, we evaluate each applicant individually. If you have excellent credit (typically 720 and up), substantial annual revenue, established banking relationships, and a solid track record, you might qualify for a reduced or even zero down payment. But remember, zero-down deals aren’t always the best choice. A smaller initial payment usually means higher monthly payments, more total interest paid over the life of the loan, and slower equity growth in your equipment.
Many of our happiest clients choose the sweet spot—putting down between 10-15%. It helps secure better terms while preserving critical cash for other business needs, balancing affordability with overall cost-effectiveness.
How long are the typical financing terms for tractor trailers?
Tractor trailer financing typically ranges from about 24 months to 72 months (2-6 years). Most borrowers find the best balance between affordability and total cost in the 36 to 60-month range. The exact term length you qualify for usually depends on the age of the equipment, your credit profile, and lender guidelines.
If you’re financing older equipment (typically 7+ years old) or facing credit challenges, lenders often prefer shorter terms (24-36 months). For newer equipment (1-3 years old), the financing terms commonly range between 48 and 72 months. Some lenders even offer terms as long as 84 months for brand-new trucks, although these extended terms often come with slightly higher interest rates.
At Noreast Capital, we help you weigh several factors when selecting your term length. You’ll want to consider how much you can comfortably afford monthly, the total interest you’ll pay over time, and how well the financing term matches your equipment’s useful life. Ideally, you’ll want your loan to be fully paid off before your truck requires major maintenance or replacement. Your business cash flow cycles and any tax implications are other important considerations when deciding on term length.
One of our clients operating a small fleet in Washington, DC opted for a 48-month financing term. Even though the monthly payments were slightly higher than a 60-month plan, it meant paying less overall interest and ensured the trucks would be fully paid before needing significant overhauls. This thoughtful approach can save thousands in the long run!
If you have questions about the best financing term for your tractor trailer, our friendly team at Noreast Capital is always happy to help you crunch the numbers!
Conclusion
Navigating tractor trailer financing doesn’t have to feel overwhelming. With the right approach and a bit of preparation, you can confidently choose financing solutions custom perfectly to your business needs.
Throughout this guide, we’ve explored several ways you can finance your tractor trailer—from traditional loans and leasing to rent-to-own and dealer financing. But what’s most important is choosing the option aligned with your unique business goals, cash flow, and growth plans.
It’s always smart to carefully weigh total costs, not just monthly payments. Remember to consider interest rates, fees, potential tax advantages, and how financing fits into your overall business plan. Knowing these details upfront can prevent costly surprises later.
Another critical factor to your success is preparation. Having your documents ready before approaching lenders, understanding your credit profile, and crafting a strong business plan can boost your chances of approval dramatically. And if your credit isn’t quite perfect, don’t worry—there are still options like larger down payments, co-signers, or specialized lenders who can help you secure the financing you need.
Whether you’re a seasoned fleet owner or an aspiring first-time buyer, partnering with a lender who truly understands the trucking industry can make all the difference. At Noreast Capital, our team’s expertise means we don’t just offer standard solutions—we provide personalized, flexible, and transparent financing options that genuinely support your business.
We serve businesses across Annapolis, Baltimore, and Washington, DC, and our commitment runs deeper than just closing deals. We aim to build lasting relationships by guiding you at every stage—whether that’s helping you select the best financing terms, steer complex paperwork, or avoid common pitfalls.
As you take the next exciting step toward acquiring your tractor trailer, we encourage you to explore our comprehensive tractor financing options and see how Noreast Capital can help. If you’re curious about your affordability and budget, try our handy Tractor Financing Calculator to build a realistic financial plan.
And remember, you’re not alone on this journey. We’re here for you, ready to answer questions, discuss your specific needs, and create a plan that keeps your business rolling forward smoothly.
Feel free to reach out and find how our expertise in tractor trailer financing can fuel your business’s growth and success.

Here’s a quick recap of key points to remember as you pursue your tractor trailer financing:
- Understand your financing options inside and out to choose what’s best for your business.
- Prepare thoroughly with documentation, credit knowledge, and a strong business plan.
- Evaluate total costs beyond just monthly payments, including long-term impacts.
- Consider your unique business circumstances (seasonality, growth projections, equipment lifecycle).
- Partner with industry experts like Noreast Capital who can offer personalized financing solutions, guidance, and support.
At Noreast Capital, we’re passionate about helping businesses like yours thrive. Let’s get your wheels turning in the right direction—together.