

Used tractor financing is a critical resource for farmers looking to expand or upgrade their machinery without the burden of full upfront costs. For those searching for quick insights:
- Affordable Options: Used tractors are generally cheaper than new, allowing easier access to finance.
- Flexible Financing: Terms can be custom to fit varying budgets and payment schedules.
- Preserve Cash Flow: Lower initial costs mean more money for other farm or business operations.
Purchasing equipment is one of the most significant investments for any farm. Used tractor financing is a practical and cost-effective solution that gives farmers access to the equipment they need without straining their financial resources. Taking advantage of these financing options can help farmers maintain steady cash flow, manage their debt wisely, and invest in modern technology.
As Vincent Cerniglia from Noreast Capital Corporation, I’ve helped numerous businesses secure financing for essential equipment, ensuring they maximize their resources while minimizing costs. My expertise lies in understanding the diverse needs of agricultural operations and delivering financing solutions that lead to long-term success.
Quick used tractor financing definitions:
– farm tractor financing
– tractor financing options
– tractor financing calculator
Understanding Used Tractor Financing
When considering used tractor financing, understand the various options available and the requirements you need to meet. Let’s break it down:
Financing Options
1. Loans and Leases:
– Loans: These are straightforward. You borrow money to buy the tractor and then pay it back over time with interest. This option is ideal if you plan to own the tractor long-term.
– Leases: Leasing a tractor can be a great choice if you want lower monthly payments and the flexibility to upgrade equipment regularly.
2. Flexible Terms:
– Financing terms can range from 12 to 84 months, allowing you to choose a plan that fits your budget. Shorter terms usually mean higher monthly payments but less interest paid overall. Longer terms offer lower monthly payments but might cost more in interest.
Credit Score Requirements
Your credit score plays a crucial role in securing financing. A higher score typically means better interest rates and more favorable terms. Here’s a quick look at how credit scores can impact your financing:
- Excellent Credit (750+): Access to the lowest interest rates and best terms.
- Good Credit (700-749): Still eligible for competitive rates, though slightly higher than those with excellent credit.
- Fair Credit (650-699): You may face higher interest rates, but financing is still accessible.
- Poor Credit (Below 650): Financing options may be limited, and interest rates could be higher. It’s essential to shop around and possibly consider improving your credit score before applying.
Loan Terms
Interest Rates:
Interest rates for used tractor financing can start as low as 1.9% for qualified buyers, but these rates depend on your credit score and the lender’s policies. It’s wise to compare rates from different lenders to ensure you’re getting the best deal.
Down Payments:
Most lenders require a down payment, typically around 10% of the tractor’s purchase price. A larger down payment can sometimes help secure a lower interest rate or more favorable loan terms.
Payment Flexibility:
Some financing options offer seasonal payment plans, which can be beneficial for farmers whose income fluctuates throughout the year. This flexibility helps manage cash flow during slower periods.
Understanding these aspects of used tractor financing can help you make informed decisions that align with your financial goals and operational needs. By carefully considering your options, you can secure the equipment you need while maintaining a healthy financial position.

Top Tips for Securing the Best Financing Deals
When you’re in the market for a used tractor, finding the best financing deal is key. Here are some top tips to help you steer the process:
Interest Rates
Shop Around for the Best Rates:
Interest rates can vary widely between lenders. It’s essential to compare rates to ensure you’re getting the best possible deal. For qualified buyers, rates can be as low as 1.9%, but this is often contingent on having a strong credit score.
Negotiate Your Rate:
Don’t be afraid to negotiate with lenders. If you have a good credit score, use it as leverage to secure a lower rate. Even a small reduction in interest can save you a significant amount over the life of the loan.
Down Payments
Consider a Larger Down Payment:
While most lenders require a minimum down payment of around 10%, putting down more can be beneficial. A larger down payment might lower your interest rate or improve your loan terms. It also reduces the total amount you need to finance, which can decrease your monthly payments.
Plan Your Budget:
Before committing to a down payment, ensure it fits within your budget. While a larger down payment can save money in the long run, it shouldn’t strain your finances upfront.
Loan Terms
Choose the Right Term Length:
Loan terms for used tractors typically range from 12 to 84 months. Shorter terms mean higher monthly payments but less interest paid over time. Longer terms offer lower monthly payments but can cost more in interest.
Consider Seasonal Payment Options:
For those in agriculture, income can be seasonal. Some lenders offer seasonal payment plans that align with your income flow, providing flexibility and helping maintain cash flow during slower periods.
Additional Tips
Check for Hidden Fees:
Always read the fine print. Some loans come with hidden fees that can increase your cost. Be sure to ask about any additional charges before signing.
Maintain a Positive Credit History:
A good credit score not only helps secure a loan but can also improve the terms. Pay bills on time and manage debt responsibly to keep your credit score healthy.
By keeping these tips in mind, you can secure a financing deal that meets your needs and supports your farming operations effectively. This will ensure you’re not just getting a tractor, but also a financial arrangement that works in your favor.
How to Apply for Used Tractor Financing
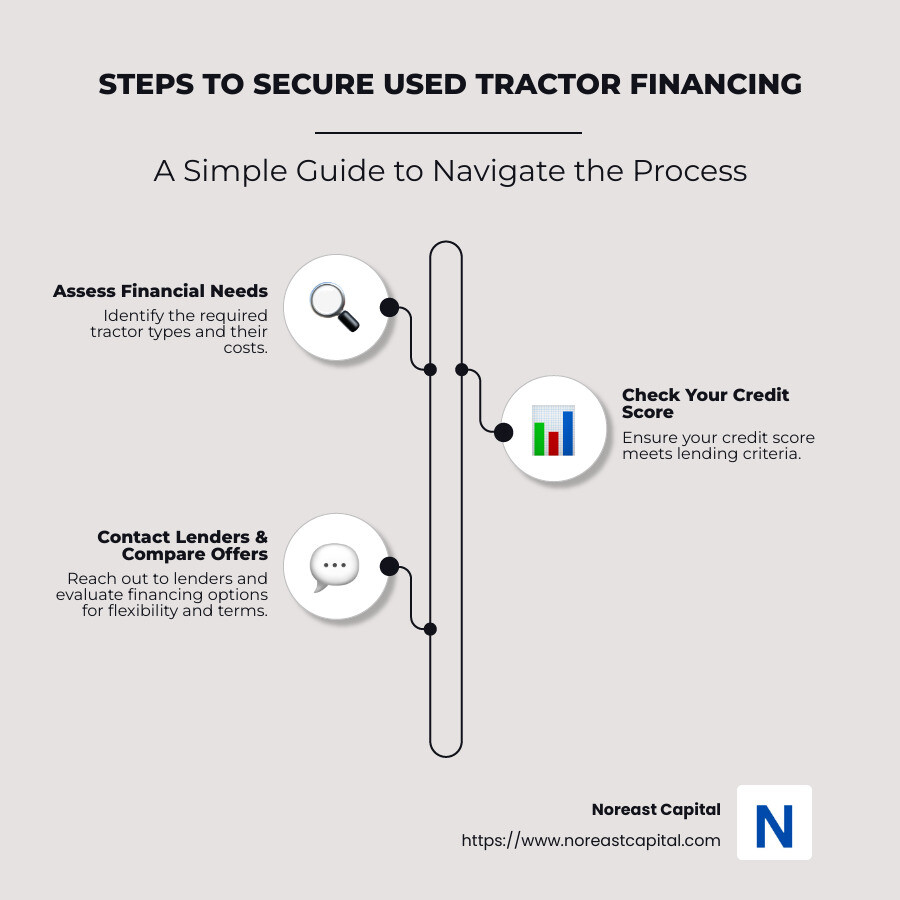
Applying for used tractor financing might seem daunting, but breaking it down into simple steps can make the process straightforward and stress-free. Here’s how to steer it effectively:
Application Process
Prepare Your Documents:
Before you start, gather essential documents such as proof of income, tax returns, and details about the tractor you wish to purchase. Having these ready will streamline the application process.Complete the Application Form:
Most lenders offer easy online applications. You can fill out forms from the comfort of your home. Be sure to provide accurate and complete information to avoid delays.Submit for Pre-Approval:
Pre-approval gives you a good idea of how much you can borrow and at what rate. It involves a soft credit check, which doesn’t affect your score. This step helps you shop with confidence, knowing your budget.
Pre-Sale Credit Decisions
Understand Your Credit Score:
Your credit score plays a crucial role in the financing terms you receive. While a score of 650 or above is often ideal, options exist for those with lower scores. Knowing your score helps in setting realistic expectations.Negotiate Terms:
If pre-approved, you can negotiate better terms based on your creditworthiness. Use this opportunity to potentially lower your interest rate or adjust the loan length to better suit your needs.
Online Applications
Convenience and Speed:
Applying online is not only convenient but also quick. Many lenders offer decisions within the same day, especially for loans up to $75,000. This speed can be critical if you’re in a hurry to secure your equipment.Secure Platforms:
Ensure the lender’s platform is secure. Look for HTTPS in the URL and read reviews to confirm the lender’s credibility. This protects your personal information during the application process.Follow Up:
After submitting your application, follow up with the lender if you don’t receive a timely response. This shows your interest and ensures your application hasn’t been overlooked.
By following these steps, you can efficiently steer the application process for used tractor financing. This preparation will help you secure the financing you need with terms that align with your financial strategy.
Frequently Asked Questions about Used Tractor Financing
Can you finance used tractors?
Yes, you can finance used tractors. Many lenders, including Noreast Capital, offer custom financing options for used equipment. This means you don’t have to pay the full price upfront, making it easier to manage your cash flow.
Lenders assess your credit score to determine the terms of your loan. A higher credit score can mean better terms like lower interest rates or smaller down payments. However, even if your credit score isn’t perfect, there are still options available. Some lenders specialize in working with those who have less-than-perfect credit.
What credit score is needed to finance a tractor?
The minimum credit score needed to finance a tractor can vary by lender. Generally, a score of 650 or above is ideal for securing favorable terms. However, many lenders, including some online ones, consider applicants with lower scores. They may offer different terms, such as higher interest rates or larger down payments.
It’s important to know your credit score before applying. This knowledge helps set realistic expectations and prepare you for potential discussions with lenders.
What are the best financing options for used tractors?
The best financing options for used tractors depend on a few factors like interest rates, loan amounts, and your credit profile. Here are some key considerations:
Interest Rates:
Look for competitive rates. Rates can vary widely, so it’s wise to shop around. Some lenders offer rates as low as 1.9% for qualified buyers.Loan Amounts:
The amount you need can influence your financing terms. Larger loans might have better rates due to economies of scale, but they also represent a bigger risk to lenders.Online Lenders:
These can offer convenience and speed. You can often complete the process from start to finish without leaving your home. Just ensure the platform is secure.Flexible Terms:
Some lenders offer terms ranging from 12 to 84 months. Choose a term that aligns with your financial strategy and cash flow needs.
By understanding these factors and preparing accordingly, you can secure the best financing deal for your used tractor. This allows you to invest in your farm’s future without straining your current finances.
Conclusion
When it comes to used tractor financing, Noreast Capital stands out as a reliable partner. We understand that maintaining cash flow is crucial for any business, especially in agriculture. That’s why our financing solutions are designed to help you use equipment without the burden of ownership. This approach allows you to save money and keep your cash flow healthy.
Why Choose Equipment Leasing?
Leasing equipment offers several advantages:
Cash Flow Maintenance:
By leasing, you avoid tying up large sums of money in equipment purchases. This leaves more cash available for other business needs, like buying seeds or paying wages.Flexibility:
Leasing agreements can be custom to fit your financial situation. You have the option to upgrade to newer models as technology advances, without the hassle of selling old equipment.Tax Benefits:
Leasing may offer tax advantages, such as the ability to deduct lease payments as business expenses. This can further improve your cash flow.Avoiding Obsolescence:
Technology in agriculture is always evolving. Leasing allows you to keep pace with these changes without being stuck with outdated equipment.
Noreast Capital’s Commitment
At Noreast Capital, we are committed to providing flexible, straightforward financing options. Our process is simple and designed to meet the unique needs of your operation. Whether you’re upgrading your fleet or replacing an older model, our team is here to support you every step of the way.
Explore our tractor financing options to find the best fit for your farm’s needs. We’re here to help you plow through the best deals and drive your business forward.