

Navigating Your Path to Affordable Lawn Care Equipment
Riding mower rent to own programs offer a flexible payment solution for those who need quality lawn equipment without the high upfront costs. Here’s what you need to know:
- No credit check required in most programs
- Low bi-weekly payments starting at $66 for riding mowers
- $0 down payment options widely available
- Free delivery and setup included with most agreements
- 12-month path to ownership typical for most agreements
- Early purchase options available (usually within 90-120 days)
- Maintenance and repairs often included at no extra cost
Are you looking to maintain your property with professional-grade equipment without breaking the bank? Riding mower rent to own programs provide an accessible alternative to traditional financing, especially for those with less-than-perfect credit scores. These programs allow you to make affordable weekly or bi-weekly payments while using the equipment immediately, eventually leading to full ownership.
Unlike traditional loans that require good credit and large down payments, rent-to-own agreements focus on your income stability rather than credit history. This makes quality riding mowers accessible to the 41% of Americans with credit scores below 700, according to Experian data.
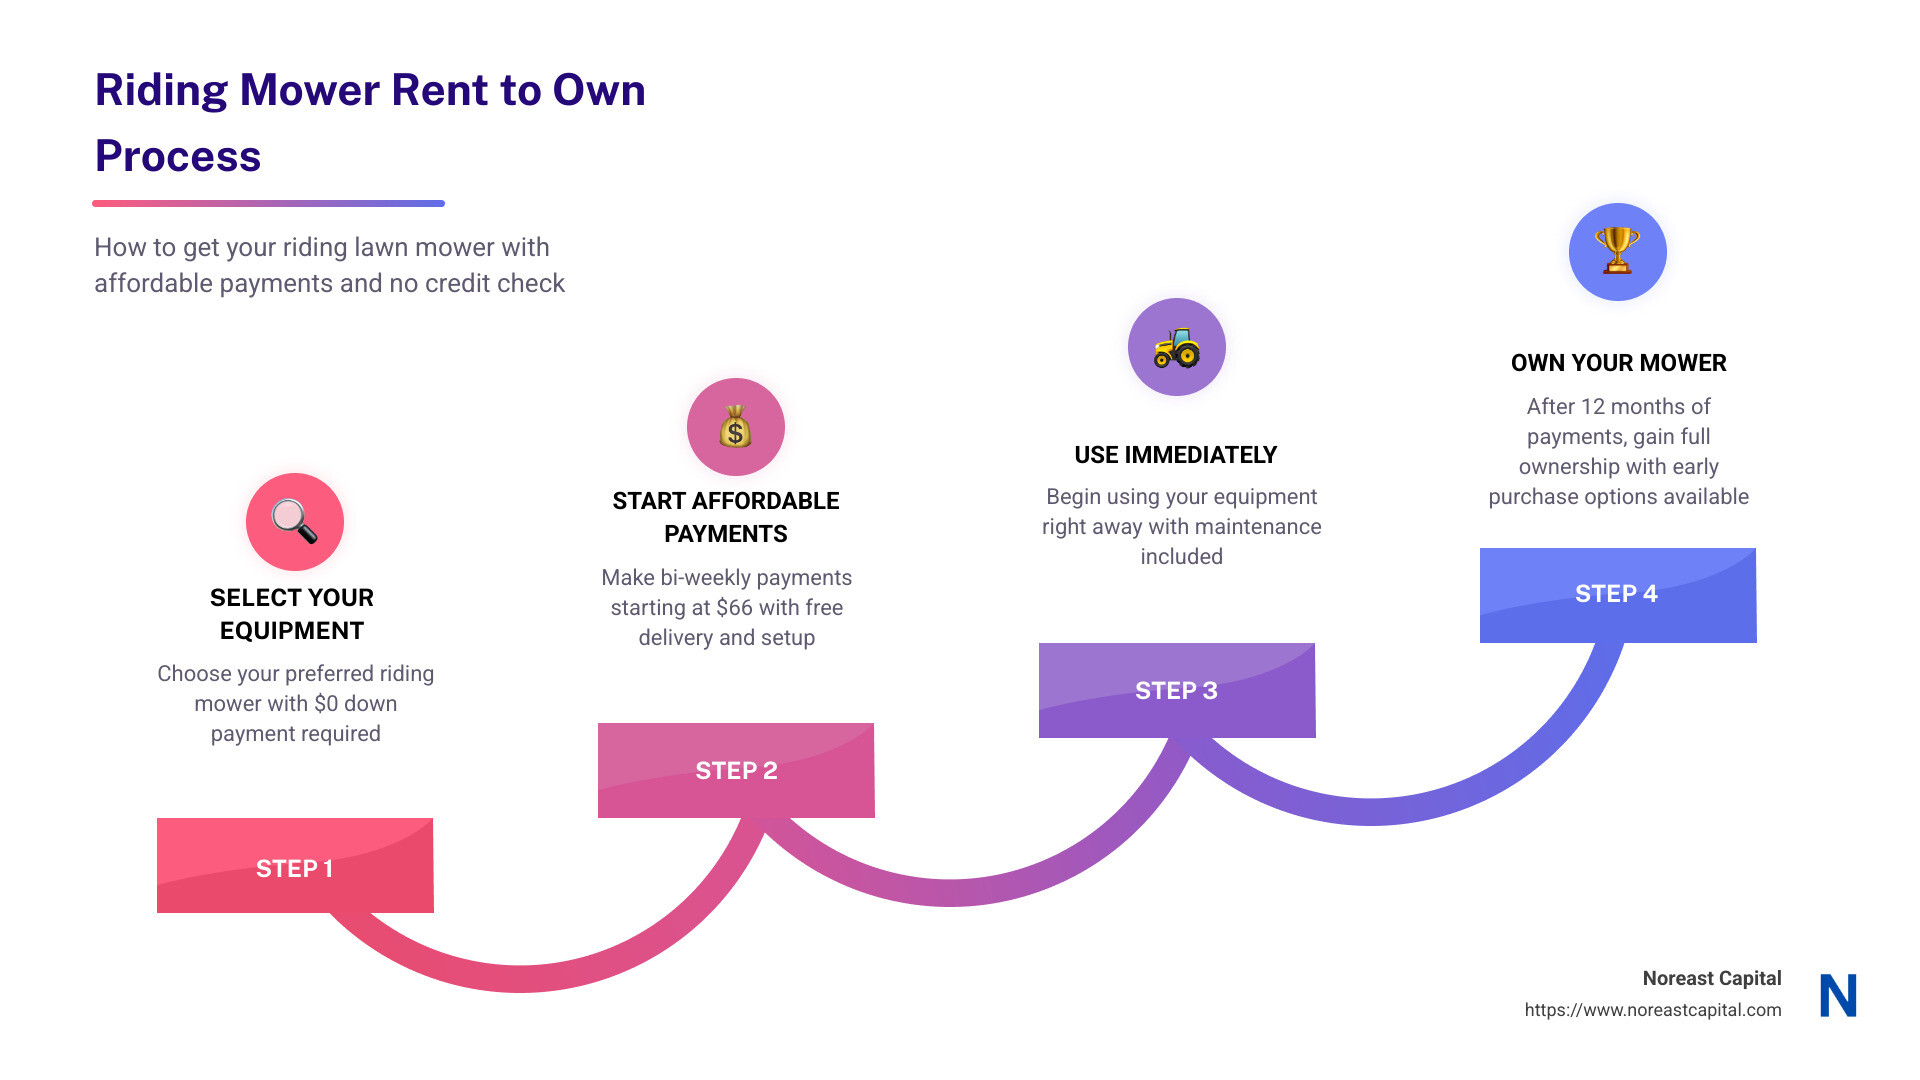
The process is straightforward: select your preferred mower, make an initial payment (often as low as $59), and continue making regular payments until you own the equipment outright. Many programs include valuable extras like free delivery, professional setup, and ongoing maintenance services.
I’m Vincent Cerniglia from Noreast Capital, where I’ve helped countless business owners steer riding mower rent to own programs to acquire the equipment they need while preserving their cash flow and credit lines. My experience in equipment financing has shown that flexible payment solutions can be a game-changer for both personal and commercial lawn care needs.
Riding mower rent to own vocabulary:
What Is Rent to Own for Riding Lawn Mowers?
When you’re looking at that beautiful yard but don’t have the cash to buy a riding mower outright, riding mower rent to own programs offer a practical middle path. Think of it as the “try before you buy” approach to lawn equipment—but with a guaranteed path to ownership.
Unlike traditional loans where a bank gives you money to purchase equipment immediately, a rent-to-own agreement works differently. The leasing company purchases the riding mower first, then lets you use it while you make regular payments. Each payment brings you closer to full ownership of that shiny new mower.
Most riding mower rent to own agreements run for about 12 months. Once you complete all payments, the mower is 100% yours—no strings attached, no balloon payments, no surprises.
“The beauty of lease-to-own programs is that they create opportunities for folks who might not qualify for traditional financing,” says Vincent from Noreast Capital. “We actually own the equipment until the final payment, which allows us to be more flexible with approval requirements and payment terms.”
How Does Rent to Own Work?
The riding mower rent to own process is refreshingly straightforward. You start by picking out the perfect mower for your needs—whether that’s a speedy zero-turn for your sprawling property or a more modest lawn tractor for weekend maintenance.
After selecting your ideal machine, you’ll complete a simple application. Don’t worry—you won’t need perfect credit. Instead, you’ll typically need:
- A valid photo ID
- Proof of income (usually around $1,300 monthly minimum)
- Basic checking account information
- Contact details for delivery
Once approved, you’ll sign an agreement that clearly spells out your payment schedule (weekly, bi-weekly, or monthly), the total number of payments required, and any early purchase options. Your first payment might be as low as $59, depending on the program and equipment.
The best part? Your new riding mower gets delivered directly to your home—often with free setup included. You can start mowing right away while making regular payments, typically through automatic withdrawals from your bank account for convenience.
After completing your payment schedule, the ownership transfers to you automatically. No additional paperwork, no extra fees—the mower is yours to keep.
One landscaper I worked with put it perfectly: “I was spending hours with a push mower on my clients’ properties. The riding mower rent to own program let me upgrade my equipment immediately, finish jobs faster, and take on more clients—all while making payments that fit my seasonal income. By the time I made the final payment, the mower had already paid for itself in new business.”
This flexibility makes rent-to-own particularly valuable for seasonal businesses, homeowners with varying income, or anyone who wants to preserve their credit lines for other purposes while still getting the equipment they need right away.
Benefits of Rent to Own vs Traditional Financing
When you’re looking to get a new riding mower, the way you pay for it matters almost as much as which model you choose. Riding mower rent to own programs offer some distinct advantages that might make them a better fit for your situation than traditional bank loans or credit cards.

Advantages Over Traditional Financing
The difference starts right at the beginning of your journey. With traditional financing, you’re often looking at putting down 10-20% of the purchase price upfront. For a quality $3,000 riding mower, that’s $300-$600 you need to have saved. Riding mower rent to own programs typically ask for much less to get started – sometimes as little as $59, and many offer true $0 down options.
“I was shocked when I found out I could get the exact mower I wanted delivered to my house without any money down,” shares Mark, a recent customer. “With three kids in sports, coming up with several hundred dollars at once would have been tough.”
Credit accessibility is perhaps the biggest game-changer here. Banks and credit unions usually want to see credit scores of 650 or higher before they’ll consider your application. Rent-to-own programs take a more holistic approach, considering your income stability and other factors beyond just your credit score. This makes quality equipment accessible to a much wider range of people – including the 41% of Americans with credit scores below 700, according to recent data.
What many folks don’t realize is that riding mower rent to own agreements typically come with valuable extras bundled in. Free delivery and professional setup saves you the hassle of figuring out how to transport a 500+ pound machine. Regular maintenance during the lease period helps keep your mower running smoothly. And if something goes wrong? Repair services are often included at no extra cost. These perks alone can save you hundreds of dollars over the life of your agreement.
Flexibility is another major advantage. Life happens, and sometimes our circumstances change. With traditional loans, you’re locked in until you pay it off. But rent-to-own programs typically offer options to:
- Purchase early if your finances improve
- Return the equipment if your needs change
- Upgrade to newer models
- Adjust payment dates to align with your payday
For small business owners like landscapers, the predictable payment structure helps tremendously with budgeting. Rather than depleting your working capital with one large purchase, you can spread the cost over time while immediately putting the equipment to work generating income.
“I was able to take on three new lawn contracts immediately after getting my zero-turn mower through the rent-to-own program,” explains Carlos, a landscaping business owner. “The mower essentially paid for itself while I was making the payments.”
Another often-overlooked benefit is that unlike traditional loans that appear as debt on your credit report, rent-to-own agreements typically don’t impact your debt-to-income ratio. This can help preserve your borrowing capacity for other needs, like a home mortgage or car loan.
As Jenny from Noreast Capital puts it, “We’ve helped countless customers who initially came to us after being turned down by traditional lenders. Our rent-to-own structure allowed them to access the equipment they needed while building toward ownership on terms that worked for their specific situation.”
When you consider all these advantages together – lower upfront costs, credit accessibility, included services, payment flexibility, and cash flow benefits – it’s easy to see why riding mower rent to own programs have become such a popular option for both homeowners and small business owners alike.
Types of Riding Lawn Mowers Available for Rent to Own
When exploring riding mower rent to own options, you’ll find a variety of equipment types to match different property sizes, terrains, and specific lawn care needs. Understanding the distinctions between these options will help you select the right equipment for your situation.

Zero-Turn Mowers
Zero-turn mowers are the sports cars of the lawn care world. If you’ve ever watched a professional landscaping crew zip around a property with impressive speed and precision, you’ve likely seen these mowers in action. What makes them special? Their ability to pivot 180 degrees on the spot means you can steer around flower beds, trees, and other obstacles without awkward three-point turns.
These mowers aren’t just about fancy maneuvers though – they’re serious time-savers. With cutting speeds of 7-10 mph (compared to 3-4 mph for standard riders), you can slash your mowing time nearly in half. This makes them perfect for larger properties where traditional mowing might eat up your entire Saturday.
When it comes to riding mower rent to own terms, zero-turns typically start around $106 bi-weekly, with monthly options ranging from $210-$329. For top-tier models with all the bells and whistles, weekly payments might reach around $75.99. Yes, they’re a bit pricier than standard riders, but many homeowners with acre-plus properties find the time savings well worth the investment.
Zero-turns shine brightest on properties larger than an acre, especially yards with landscaping features that require precise navigation. Professional landscapers love them for their efficiency, but even homeowners who simply value their weekend time find them to be game-changers.
Lawn Tractors and Garden Tractors
If zero-turns are the sports cars, lawn tractors are the reliable family sedans of the mowing world. They offer that perfect balance of affordability, user-friendliness, and versatility that makes them America’s most popular riding mower choice.
What makes lawn tractors so approachable is their familiar car-like controls – a steering wheel instead of lap bars, straightforward operation, and comfortable high-back seats that make those longer mowing sessions less taxing on your body. They typically feature cutting widths between 42″ and 48″, striking a nice balance between efficiency and maneuverability.
Garden tractors, meanwhile, are like the pickup trucks of the lawn equipment world – built with beefier frames and more powerful engines to handle tasks beyond just mowing. Want to till a garden bed, haul a cart of mulch, or plow snow in winter? A garden tractor with the right attachments can be your year-round outdoor workhorse.
The riding mower rent to own options for these tractors are particularly budget-friendly, with payments starting as low as $66 bi-weekly for standard models. Monthly payments typically range from $179.99 to $239.99, while weekly options hover between $41.54 and $60.00. These more accessible payment plans make lawn tractors the go-to choice for many homeowners just entering the riding mower market.
These tractors are ideal companions for properties between half an acre and two acres. They’re perfect for homeowners who appreciate traditional controls and might need occasional versatility beyond just cutting grass. The ability to add seasonal attachments means your investment works for you year-round, not just during growing season.
Many of the models available through Noreast Capital’s riding mower rent to own programs feature durable steel decks, user-friendly 7-speed transmissions, and reliable engines ranging from 15.5HP to 19HP. The popular 42″ deck size hits the sweet spot – wide enough for efficiency but narrow enough to fit through standard gates and into typical storage sheds.
Whether you’re maintaining a sprawling country property or a suburban lot with too much lawn for a push mower, there’s a rent-to-own riding mower that fits both your property needs and your budget. And the best part? You can start using it right away while building toward ownership with payments that work for your household budget.
Riding Mower Rent to Own Payment Terms and Costs
When you’re considering a riding mower rent to own program, understanding exactly what you’ll pay and how the payments work is crucial. Let’s break down these agreements in simple terms so you can decide if they’re right for your situation.
Understanding Bi-Weekly and Monthly Payments
One of the best things about riding mower rent to own programs is their payment flexibility. Most companies, including us at Noreast Capital, offer several payment schedules to match how you get paid and manage your household budget.
If you’re paid weekly, you might prefer weekly payments, which typically range from about $41 to $60 for standard models. These are the smallest individual amounts, making them easier to fit into tight budgets.
Bi-weekly payments are incredibly popular since they often align perfectly with common paycheck schedules. For a standard lawn tractor, you might pay around $66 to $76 every two weeks. This option gives you a nice balance between manageable payment size and fewer total transactions.
If you prefer to make just one payment per month, monthly options generally range from about $180 to $240 for standard models. While these are larger individual payments, you’ll only need to think about them once a month.
Most programs require enrollment in automatic payment systems (often called EZPay or Autopay). While this might seem restrictive at first, it actually comes with several benefits. You won’t have to remember to make payments, you’ll avoid late fees, and you can usually choose a payment date that works best with your income schedule. In many cases, automatic payments even qualify you for lower overall rates!
The standard agreement length for most riding mower rent to own programs runs for 12 months (52 weeks). For those who need even lower payments, some companies offer extended terms of 78 weeks, 104 weeks, or even 130 weeks for premium equipment. Just remember that longer terms mean smaller individual payments but a higher total cost in the long run.
Early Purchase Options and Total Cost
Here’s where you can potentially save a significant amount of money. Most rent-to-own agreements include what’s called a “Same as Cash” option. This means you can purchase the equipment outright within a specific timeframe at a much lower total cost than if you continued making all the scheduled payments.
This early purchase window typically extends for 90-120 days after your agreement starts. (California residents should note that state regulations often limit this period to 90 days.) Some companies offer loyalty programs where club members receive extended periods of up to 180 days.
For example, if you’re looking at a mower with a retail price of $3,120, paying it off during the “Same as Cash” period could save you thousands compared to making all scheduled payments through the full term.
When evaluating the total cost, it helps to understand the complete structure:
First, there’s the cash price – the retail value of the equipment (let’s say $3,120 in our example). Then there’s the cost of lease services – the additional fees for the rent-to-own structure (perhaps around $2,230). Together, these create the total cost of ownership if you make all payments through the full term (approximately $5,400 in this scenario).
“While our total cost over time may exceed the retail price,” as we often explain to customers at Noreast Capital, “we include delivery, setup, and maintenance services that would otherwise be separate expenses. Plus, many customers use our early purchase options to significantly reduce the overall cost.”
For many people with limited financing options or immediate lawn care needs, the additional cost represents a fair trade-off for accessibility, included services, and the ability to start using professional-grade equipment right away. The key is understanding your options and planning accordingly – whether that means budgeting for the full term or saving up to take advantage of those early purchase savings.
Credit Checks and Qualification Requirements
The most refreshing aspect of riding mower rent to own programs is how they open doors for folks who might get turned away elsewhere. Unlike banks that fixate on your credit score, these programs take a more human approach to figuring out if you’re a good fit.
How to Qualify for a Rent to Own Program
Getting approved for a riding mower rent to own program is surprisingly straightforward. Instead of obsessing over your credit history, these programs look at your overall stability and ability to make payments.
Most companies just want to see that you’re an adult with steady income and a bank account. You’ll typically need to be at least 18 years old with a valid government-issued photo ID. They’ll ask for your Social Security Number or ITIN, but don’t panic – they’re not using this to run an extensive credit check in most cases.
When it comes to income, you’ll need to show you earn enough to handle the payments – usually around $1,300 monthly or $12,000 annually. This can come from a regular job, self-employment, benefits, or other consistent sources. A few recent pay stubs or bank statements usually do the trick.
You’ll also need an active checking account in good standing for the automatic payments. Most companies require this since it helps ensure timely payments and simplifies the process for everyone involved.
“We designed our application process to be quick and painless,” one of our specialists at Noreast Capital explained. “Most customers find out if they’re approved within minutes, not days.”
Do Rent to Own Programs Require Credit Checks?
Here’s where riding mower rent to own programs really shine compared to traditional financing. The approach to credit checks varies between providers, but most follow one of these paths:
Many programs proudly advertise “No Credit Needed” policies, making quality equipment accessible regardless of your credit history. As one of our team members likes to say, “Your past financial hiccups don’t define your future with us.”
Some providers might perform a “soft pull” of your credit information, which gives them basic insights without affecting your credit score. This is just one piece of the puzzle, not a make-or-break factor.
What’s most refreshing is how these programs often use alternative evaluation methods that look beyond traditional credit scores. They consider factors like how stable your income is, how long you’ve been at your job, and your banking history. This holistic approach means even folks with limited or imperfect credit can qualify.
“When we say ‘no credit needed,’ we mean we’re not making decisions based solely on a three-digit number,” explains Vincent from Noreast Capital. “We understand that life happens – medical bills, divorce, job loss – and these situations shouldn’t permanently block you from getting the equipment you need.”
This inclusive approach has been a game-changer for young adults just starting out, self-employed individuals with non-traditional income, and people rebuilding after financial setbacks. Many of our customers come to us after being declined by traditional lenders, relieved to find a company that sees their current situation rather than just their credit history.
At Noreast Capital, we’ve helped countless customers access quality riding mowers despite past credit challenges. We believe equipment financing should be about your future needs, not just your past financial history.
Early Payoff and Managing Missed Payments
Let’s face it – life doesn’t always go according to plan. The good news is that riding mower rent to own programs offer remarkable flexibility when it comes to managing your payments. Whether you’re looking to pay off your mower early or need to adjust your payment schedule, these programs typically provide options that traditional financing simply doesn’t match.
What If You Can’t Make Payments?
We all face unexpected financial challenges sometimes. Maybe your hours got cut at work, or perhaps an emergency expense drained your bank account. The companies behind riding mower rent to own programs understand this reality and generally offer several ways to handle payment difficulties.
First, most programs allow you to adjust your payment date to better align with your payday schedule. Just contact customer service at least three business days before your scheduled payment, and they can typically shift your payment date to a more convenient time. This simple adjustment can make all the difference in keeping your account current.
If your financial situation becomes more challenging, you have the option to return the equipment without the severe penalties you’d face with traditional financing. Unlike a bank loan where missed payments damage your credit and can lead to collections, rent-to-own agreements let you return the mower and walk away without further obligation. You’ll only be responsible for payments up to the return date.
“Our customers appreciate the peace of mind knowing they can return their equipment if their circumstances change,” explains a representative from Noreast Capital. “There’s no negative impact on your credit report since we don’t report to credit bureaus.”
Perhaps most impressively, many riding mower rent to own programs offer what’s called a “Lifetime Reinstatement Benefit.” This unique feature allows you to restart your lease on the same or comparable equipment if your financial situation improves – even after you’ve returned the mower. It’s like having a safety net during temporary hardships while still maintaining your progress toward ownership.
Can You Pay Off a Rent to Own Riding Mower Early?
Absolutely! Not only can you pay off your riding mower rent to own agreement early, but doing so typically saves you a significant amount of money. Here’s how the early payoff options generally work:
The most advantageous option is the “Same as Cash” period, which exists during the first part of your agreement – typically 120 days from when you sign (though California residents are limited to 90 days, and some club members may receive up to 180 days). During this window, you can purchase the equipment outright at the original cash price, avoiding the additional lease fees that come with the full payment schedule. This approach can save you 30-50% compared to making all scheduled payments.
Even after the Same as Cash period expires, you can still purchase your mower at any point during your lease term. The payoff amount will generally fall somewhere between the original cash price and the sum of your remaining payments. The specific formula varies by provider but should be clearly disclosed in your agreement.
To exercise your early purchase option, simply contact customer service to request your current payoff amount. Once you make the one-time payment, you’ll receive confirmation that the mower is now fully yours.
“Many of our customers start with a riding mower rent to own agreement because they need the equipment immediately but can’t afford the full purchase price upfront,” notes a Noreast Capital specialist. “Then, when their tax refund arrives or they receive a bonus at work, they take advantage of the early payoff option to save on the total cost.”
These flexible payment options make riding mower rent to own programs uniquely adaptable to your changing financial situation. Whether you need to adjust your payment schedule, return the equipment temporarily, or pay off your mower early to save money, these programs put you in control of your lawn care equipment journey.
Delivery, Setup, Maintenance, and Repairs
When you choose a riding mower rent to own program, you’re getting more than just a financing plan – you’re getting a complete service package that makes the whole experience much easier. These included services are a huge part of what makes these programs so appealing to homeowners and landscaping professionals alike.

What Maintenance and Repair Services Are Included?
One of the most overlooked benefits of riding mower rent to own programs is the maintenance support that comes with your equipment. Imagine not having to worry about finding a repair shop or figuring out how to fix complex engine issues yourself!
Most programs include regular maintenance during your lease period, covering essentials like oil changes, filter replacements, and blade sharpening. These routine services would typically cost you $75-150 per visit if you were paying out of pocket, so this benefit adds real value to your agreement.
“The maintenance package alone saved me over $300 in the first year,” shares Mike, a landscaper who chose a rent-to-own zero-turn mower. “Plus, I didn’t have to spend my weekends tinkering with the engine instead of spending time with my family.”
If something goes wrong with your mower, the repair process is refreshingly simple. Just contact customer service to report the issue, and they’ll help schedule a service appointment. Many programs even offer temporary replacement equipment if repairs will take more than a day or two – a crucial benefit for those who rely on their mower for business purposes.
This comprehensive maintenance coverage ensures your equipment stays in top condition throughout the lease period. You won’t face unexpected repair bills or struggle with declining performance as the seasons pass. For many customers, this peace of mind is worth just as much as the flexible payment terms.
Delivery and Setup Options
Getting a bulky riding mower from the store to your property can be a logistical nightmare if you don’t have a truck and trailer. That’s why the free delivery service included with most riding mower rent to own programs is such a valuable perk.
Rather than renting a trailer or begging a friend with a truck for help, you can simply schedule a convenient delivery time. Most providers deliver within 5-7 business days of approval, and some even offer expedited options if you need your equipment sooner.
The delivery team doesn’t just drop the mower at the end of your driveway, either. Professional setup ensures your equipment is properly assembled, adjusted, and ready to use immediately. They’ll verify fuel and oil levels, make initial adjustments for optimal performance, and even give you a quick operational demonstration if you’re new to riding mowers.
“I was surprised by how thorough the delivery guys were,” says Jennifer, a first-time riding mower owner. “They took the time to show me how to adjust the cutting height and gave me tips on maintaining the mower between service visits. I would have been completely lost without that guidance.”
To ensure your delivery goes smoothly, it helps to prepare in advance. Clear a path for the equipment, make sure your delivery location is accessible, and be available during your scheduled window. Many programs now offer tracking options so you can follow your delivery’s progress online or receive text notifications as it gets closer.
A Noreast Capital representative puts it perfectly: “The included delivery and setup services represent a significant value—often $200-$300 if purchased separately. This ensures our customers can begin using their equipment immediately without logistical concerns or assembly challenges.”
By combining flexible financing with comprehensive service support, riding mower rent to own programs offer a complete equipment solution that goes far beyond just helping you acquire a mower. For many customers, especially those who lack mechanical experience or transportation options, these included services make all the difference.
Pros and Cons of Rent to Own Riding Lawn Mowers
When you’re considering how to get that riding mower you need, it’s important to look at the complete picture of what riding mower rent to own programs offer – both the sunny side and the potential rain clouds. Let’s explore both so you can make a choice that works for your lawn and your wallet.
Advantages of Rent to Own
The accessibility of riding mower rent to own programs is truly game-changing for many homeowners and small businesses. Unlike traditional bank loans that might turn you away for a less-than-stellar credit score, these programs often look beyond credit numbers to see the person behind the application. Many customers who’ve been rejected elsewhere find open doors here, with approval processes that consider your income stability rather than just your financial history.
Getting started couldn’t be much easier. While traditional financing might require thousands down, riding mower rent to own programs typically offer $0 down options with initial payments sometimes as low as $59. Imagine having that zero-turn mower delivered to your home this weekend instead of saving up for months or years! The application process is refreshingly straightforward too – often just a few minutes online or over the phone.
“Rent-to-own mowers include free delivery and maintenance, making them more accessible for those with budget constraints.“
One of the hidden gems of these programs is the comprehensive service package that comes along for the ride. Free delivery saves you from figuring out how to transport a 500-pound machine. Professional setup means no puzzling over assembly instructions. And ongoing maintenance during your lease period? That’s peace of mind that traditional financing simply doesn’t offer.
The flexibility built into these agreements is another major plus. If your financial situation improves, you can exercise early purchase options and potentially save substantially. If the mower isn’t quite right for your needs, you have return options that traditional loans don’t offer. You can even adjust payment dates to align with your payday – try asking your bank for that kind of flexibility!
Perhaps my favorite advantage is the “try before you fully commit” aspect. You get to really test how that mower handles your specific property – those hills, that wet spot near the creek, how it fits through your garden gate – before you’re fully invested. It’s like an extended test drive that traditional financing simply can’t match.
Disadvantages to Consider
Let’s be honest about the costs. The convenience and accessibility of riding mower rent to own programs do come with a price tag. If you calculate the total payments over the full term, you’ll typically pay more than the retail price – sometimes 30-80% more. This is the trade-off for the lower entry barrier and included services. Think of it as paying for the opportunity to build ownership gradually without perfect credit or large upfront costs.
The payment structure requires some disciplined money management on your part. Most programs use weekly or bi-weekly automatic withdrawals, which means consistently keeping sufficient funds in your account. Missing payments can trigger additional fees, and early termination might mean losing the progress you’ve made toward ownership. For folks who prefer a “set it and forget it” annual payment, this more frequent schedule might feel demanding.
Depending on which program you choose, you might find the selection somewhat limited compared to walking into a retail store. The newest, cutting-edge models might not be immediately available through rent-to-own channels, and if you need highly specialized equipment, your options could be narrower. It’s worth checking inventory before getting your heart set on a specific model.
There’s also a psychological factor to consider – the temptation to overextend. When programs focus on “just $66 bi-weekly” rather than the total commitment of $3,000+, it’s easier to convince yourself to choose a more expensive model than you might need. Some customers find themselves juggling multiple rent-to-own agreements across different product categories, creating a significant cumulative financial obligation.
As one of our advisors at Noreast Capital often tells customers: “Consider both what fits your budget today and the total investment over time. For many people, the additional cost is completely worth it for the accessibility, included services, and opportunity to build toward ownership without perfect credit – but go in with your eyes open.”
When weighing these factors against your specific situation – your credit access, immediate needs, cash flow, and long-term financial goals – you’ll be able to determine if a riding mower rent to own program is your best path to keeping that lawn looking fantastic without breaking your budget today.
Frequently Asked Questions about Riding Mower Rent to Own
What Companies Offer Rent to Own Programs for Riding Lawn Mowers?
When you’re looking for riding mower rent to own options, you’ll find several providers in the marketplace. At Noreast Capital, we specialize in equipment financing solutions that help both homeowners and businesses access quality lawn equipment without the upfront investment.
The landscape of rent-to-own providers varies widely, with some focusing exclusively on lawn equipment while others offer a broader range of products. What matters most is finding a partner whose service area, equipment selection, and terms align with your specific needs.
Before committing to any program, take time to compare a few key factors. Look at their service coverage to ensure they deliver to your location—especially important if you’re in a rural area. Check their equipment selection to verify they carry the brands and models you’re interested in. Pay close attention to their payment structure and whether they offer weekly, bi-weekly, or monthly options to match your cash flow.
Perhaps most importantly, ask detailed questions about what’s included beyond the equipment itself. Quality providers like Noreast Capital include delivery, setup, and ongoing maintenance—services that add significant value to the arrangement.
We’re proud to serve customers throughout the Mid-Atlantic region, including Annapolis, Baltimore, and Washington DC, with transparent financing solutions that keep your lawn looking great while preserving your cash flow and credit lines for other priorities.
How Do I Choose the Right Riding Mower for Rent to Own?
Selecting the perfect riding mower through a riding mower rent to own program starts with an honest assessment of your property and needs. This isn’t just about getting the biggest or fanciest model—it’s about finding the right match for your specific situation.
Your property size is the first consideration that will narrow down your options. For smaller properties under half an acre, you might not even need a riding mower (though they certainly make the job more comfortable). Properties between half an acre and an acre are ideal for standard lawn tractors, while larger properties of 1-3 acres might benefit from a more efficient zero-turn model. If you’re maintaining more than three acres, a commercial-grade zero-turn mower will save you significant time and effort.
The terrain of your property matters just as much as its size. Flat lawns give you the most flexibility in mower selection, while properties with gentle slopes require lawn tractors with good traction. If you’re dealing with steeper inclines, look for garden tractors with more powerful engines and better stability. Properties with lots of trees, flower beds, or other obstacles benefit tremendously from the maneuverability of zero-turn models.
Think about your comfort during operation too, especially if you’ll be mowing for extended periods. Features like high-back seats, ergonomic controls, and cup holders might seem like luxuries, but they make a big difference when you’re on the mower for an hour or more. Also consider practical aspects like storage space—make sure you measure your garage or shed to confirm your chosen mower will fit comfortably.
“Most customers end up using their mowers longer than they initially planned,” shares one of our equipment specialists at Noreast Capital. “It’s usually worth selecting a model with slightly more capacity than your minimum requirements—you’ll appreciate that extra cutting width or power as your needs evolve.”
Are There Hidden Fees in Rent to Own Agreements?
Transparency is essential when entering a riding mower rent to own agreement, and reputable providers should have nothing to hide about their fee structure. That said, it’s always smart to know exactly what to look for in the paperwork.
A legitimate rent-to-own agreement should clearly outline several key financial elements. You should see the initial payment amount stated plainly, along with the regular payment amount and frequency. The total number of payments required for ownership should be specified, as should any early purchase options. The agreement should also mention any potential late payment fees or processing charges that might apply under certain circumstances.
Where some customers encounter surprises is in the additional costs that might not be highlighted during the initial sales conversation. These might include state-specific processing fees that vary by location, penalties for late payments, charges for returned payments, or fees for terminating the agreement early. Some providers also charge delivery fees for remote locations, so ask about this if you live outside major service areas.
The most important sections to review carefully are those detailing the “Cost of Lease Services” (the premium you’re paying over retail price for the convenience of the rent-to-own structure), the “Total Cost of Ownership” (what you’ll pay in total if you make all scheduled payments), and the “Early Purchase Option” (which explains how and when you can buy the equipment outright at a reduced cost).
At Noreast Capital, we believe customers deserve complete clarity about what they’re signing up for. Our agreements spell out all costs associated with our equipment financing programs in plain language. We encourage potential customers to ask questions about anything that seems unclear—we’d rather spend extra time explaining our terms upfront than have any misunderstandings later.
A good practice before signing any riding mower rent to own agreement is to request a written breakdown of all costs. Compare the total cost to the retail price of the mower to understand exactly what premium you’re paying for the convenience and services included in the program. This knowledge helps ensure you’re making a fully informed decision that works for your budget and needs.
Conclusion
Finding the right path to owning a quality riding mower doesn’t have to break the bank or require perfect credit. Riding mower rent to own programs offer a refreshing alternative that puts professional-grade lawn equipment within reach for many who might otherwise struggle with traditional financing options.
Throughout this guide, we’ve explored how these programs work, from the simple application process to the flexible payment structures that accommodate various budgets. We’ve seen that while the total cost may be higher than a straight cash purchase, the included benefits like free delivery, professional setup, and ongoing maintenance add substantial value that often justifies the premium.
For many of our customers at Noreast Capital, the ability to access quality equipment without credit checks or large down payments has been a game-changer. I’ve personally helped landscapers grow their businesses with equipment they couldn’t otherwise afford upfront, and homeowners transform their properties with professional-grade mowers that retail stores wouldn’t finance due to credit concerns.
What makes riding mower rent to own truly valuable is its flexibility. Need to adjust your payment date to match your payday? No problem. Want to pay off your equipment early to save on the total cost? Most programs offer attractive early purchase options. Facing unexpected financial challenges? The ability to return the equipment without penalty provides peace of mind that traditional loans simply don’t offer.
Selecting the right mower for your specific needs is crucial. Consider your property size, terrain, and how frequently you’ll use the equipment. A good rule of thumb: it’s better to have slightly more mower than you need rather than struggling with equipment that’s undersized for your property.
At Noreast Capital, we believe equipment financing should work for you, not against you. Our riding mower rent to own programs are designed to preserve your cash flow while giving you access to the tools you need to maintain beautiful lawns and grow your business. We serve customers throughout Annapolis, Baltimore, and Washington DC with transparent terms and personalized support throughout your agreement.
Whether you’re a homeowner tackling a large property or a lawn care professional building your business, rent-to-own programs offer a practical solution that adapts to your financial reality. With the right information and a clear understanding of the terms, you can make this flexible financing option work to your advantage.
Ready to explore your options? We’re here to help you find the perfect riding mower solution for your specific needs and budget. Your perfect lawn is waiting – and it doesn’t have to wait until you can afford to pay cash or qualify for traditional financing.