

Why Equipment Financing Online is Revolutionizing Small Business Growth
Equipment financing online allows businesses to acquire essential machinery, vehicles, and technology through digital applications that can be approved and funded within 24-48 hours. Here’s what you need to know:
Top Online Equipment Financing Options:
– Application-only programs up to $200,000-$250,000
– Same-day approvals with soft credit pulls
– 100% financing including delivery and installation costs
– Funding amounts from $5,000 to $5,000,000
– Terms ranging from 2-7 years depending on equipment type
Key Benefits:
– Preserve working capital for daily operations
– Use equipment as collateral (no blanket liens)
– Potential Section 179 tax deductions up to $1,160,000
– Fixed payment schedules that match cash flow cycles
Gone are the days of lengthy bank visits and paperwork marathons. Today’s digital lending platforms can connect you with 75+ lenders through a single application, often delivering funding faster than traditional banks can schedule your first meeting.
The equipment itself typically serves as collateral, making approval easier than unsecured business loans. Whether you need construction equipment, medical devices, commercial vehicles, or IT hardware, online platforms now offer instant quotes and streamlined approvals that keep your business moving.
I’m Vincent Cerniglia, and through Noreast Capital Corporation, I’ve helped thousands of businesses steer equipment financing online to acquire the tools they need without depleting their cash reserves. Our direct lending approach has made us a leader in providing nationwide finance and leasing solutions to businesses ranging from small startups to Fortune 500 corporations.
Equipment financing online word list:
– asset based equipment financing
– capital equipment financing
How Equipment Financing Online Works
Remember when getting business financing meant sitting across from a banker who treated your loan application like it was radioactive? Those days are thankfully behind us. Equipment financing online has completely changed the game, turning what used to be a marathon into a sprint.
The magic happens because of how these digital platforms are built. Unlike traditional banks that need to verify every detail of your business life, online equipment financing works on a simple principle: the equipment you’re buying becomes the collateral. This means less paperwork, faster decisions, and way less stress.
Application-only programs let you secure up to $250,000 without drowning in financial documents. We’re talking about a one-page application instead of a three-inch binder. The equipment itself backs the loan, so lenders can move fast without taking huge risks.
Same-day approvals aren’t just marketing hype anymore – they’re the new normal. While your local bank is still scheduling your first meeting, online platforms are using smart technology to evaluate your application and give you an answer within hours.
The credit check process is gentler too. Most online lenders start with soft credit pulls that don’t ding your credit score. This means you can shop around and compare offers without worrying about hurting your credit rating.
100% financing capability is another game-changer. You’re not just financing the equipment – you can include delivery, installation, training, even extended warranties. This keeps more cash in your business account where it belongs.
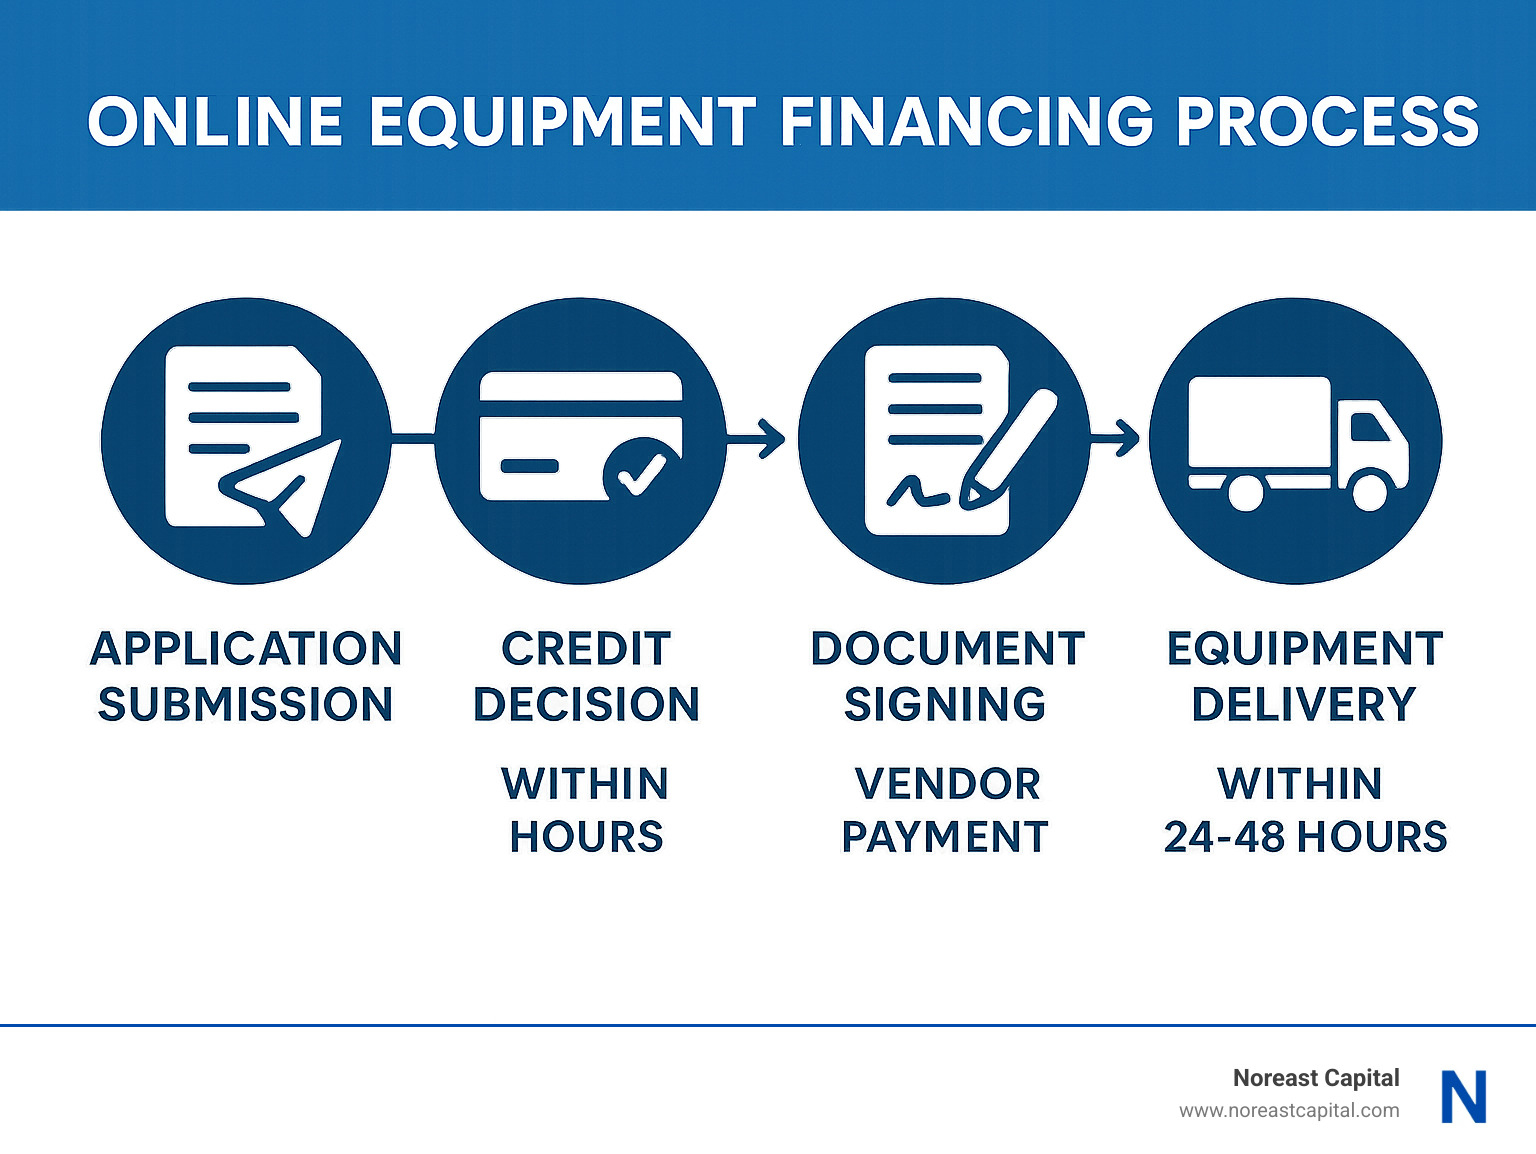
The timeline is refreshingly predictable. You submit your application today, get a decision within hours, sign documents electronically, and we pay your vendor within 24-48 hours. Your equipment ships immediately after payment.

Steps to Apply for Equipment Financing Online
The application process for equipment financing online is designed for real business owners who don’t have time to waste. We’ve stripped away everything that doesn’t absolutely need to be there.
The one-page application takes about 10 minutes to complete. You’ll need basic information like your company name, how long you’ve been in business, your annual revenue, and what equipment you want to finance.
Document submission is equally simple. Most applications need just three months of bank statements, an equipment quote or invoice, basic business info, and your driver’s license or business registration. For financing under $250,000, many lenders don’t even require financial statements.
Electronic signatures handle the paperwork once you’re approved. The documents arrive in your email, you can review everything at your own pace, and sign them from your phone if you want.
Vendor payment happens directly from us to your equipment supplier. Once we receive your signed documents, funds typically wire to the vendor within 24 hours.
Speed & Convenience of Equipment Financing Online
The convenience of equipment financing online goes way beyond just being fast. We’re talking about instant decisions, real-time tracking, and zero trips to the bank.
Instant decision technology evaluates your application using smart algorithms that can process your credit, bank activity, and business performance in minutes. Some platforms offer immediate approvals up to $20,000 without even checking your credit score.
Dashboard tracking gives you a live view of exactly where your application stands. Instead of playing phone tag with a loan officer, you can log in anytime to see if you need to submit additional documents or if funding is on the way.
No bank visits required means you can handle everything from wherever you are. Job site, office, kitchen table – doesn’t matter. As long as you have internet access, you can complete the entire process.
At Noreast Capital, we’ve helped businesses in all 50 states get the equipment they need quickly. Geography doesn’t matter anymore – a contractor in rural Montana gets the same fast service as a medical practice in downtown Baltimore.
More info about Easy Equipment Financing
What Can Be Financed & Who Qualifies
The beauty of equipment financing online is that almost any business equipment you can imagine can be financed through digital platforms. We’ve seen the lending industry accept everything from massive construction machinery to office equipment.
Construction gear tops the list for good reason. Whether you need excavators, bulldozers, cranes, concrete pumps, or dump trucks – they’ve all been financed through applications that took less time to complete than your morning coffee break.
Medical devices represent one of our fastest-growing categories. Healthcare practices are finding they can get that new diagnostic imaging equipment or dental chair without wiping out their cash reserves. From X-ray machines to laboratory equipment, medical professionals are using online financing to stay current with technology.
Your commercial vehicles qualify too. Food-truck entrepreneurs, delivery services, construction companies with fleets – everyone’s finding that financing trucks, vans, and specialty vehicles online beats the traditional dealer-financing runaround.
IT hardware financing has exploded as businesses realize their computer systems and software are just as critical as heavy machinery. Network equipment, servers, phone systems – if it plugs in or boots up, there’s probably a lender willing to finance it online.
Don’t overlook office furniture and everyday equipment. Those ergonomic chairs, conference-room setups, and industrial-grade copiers all qualify for financing.
Used equipment opens doors for budget-conscious businesses. Equipment up to 10 years old can often be financed, giving you access to quality machinery at a fraction of new-equipment costs.

The qualification requirements for equipment financing online are refreshingly straightforward compared to traditional bank lending. Since the equipment itself serves as collateral, lenders can be more flexible with other requirements.
Startups shouldn’t feel left out of the equipment-financing game. Many online lenders have programs specifically designed for newer businesses, recognizing that every successful company started somewhere.
Bad-credit options exist because lenders understand that past financial challenges don’t necessarily predict future success. If your credit score took a hit but your business is generating revenue, there are programs designed to help you get the equipment you need.
Most lenders look for a minimum credit score between 520-650, though some specialized programs work with scores as low as 500 for smaller transactions. Your time in business matters too – while 2+ years is preferred, many lenders work with businesses that have been operating for just 6-24 months.
Revenue requirements typically start around $50,000 annually, though some lenders will consider businesses generating as little as $25,000 per year. The key is demonstrating consistent cash flow that can support equipment payments.
According to research from the Small Business Administration, equipment financing represents billions in annual lending volume, proving that businesses across America are using these tools to grow and modernize. The U.S. Small Business Administration also highlights access to capital as a top challenge for growing firms, making flexible options like online equipment financing even more valuable.
Eligibility Checklist for Equipment Financing Online
Getting your documentation ready before applying for equipment financing online can turn a potentially stressful process into a smooth experience.
- Credit score information – include both business and personal credit reports if available. If there are any credit issues, a simple explanation letter can help lenders understand the circumstances.
- Revenue proof – typically your last three to six months of bank statements. For larger transactions, you might need tax returns or profit-and-loss statements.
- Bank statements that show consistent deposits and responsible account management.
- Have your equipment invoice or quote ready with all the details: specifications, model numbers, vendor contact information, and delivery timeline.
Loans vs. Leases: Choosing the Best Product
Choosing between equipment loans and equipment leases can feel overwhelming, but it doesn’t have to be. Both options are available through equipment financing online platforms, and the right choice depends on your business goals, cash flow needs, and how you plan to use the equipment.
Think of it this way: buying is like owning your home, while leasing is more like renting with the option to buy later.
Equipment loans give you immediate ownership of your equipment. You’re borrowing money to buy the asset outright, which means you can modify it, sell it, or use it as collateral for future financing. The ownership benefits are significant – you build equity with every payment, and once the loan is paid off, the equipment is yours free and clear.
From a tax perspective, loans offer solid advantages. You can depreciate the full purchase price and deduct interest payments. Plus, there are no restrictions on how you use the equipment.
Equipment leases work differently. The leasing company owns the equipment, and you’re essentially renting it with potential ownership at the end. The biggest draw? Lower monthly payments – typically 10-30% less than loan payments. This preserves more of your working capital for daily operations.
Leases also offer upgrade flexibility. When your lease ends, you can often upgrade to newer technology without the hassle of selling old equipment. For businesses in fast-changing industries, this flexibility is invaluable.
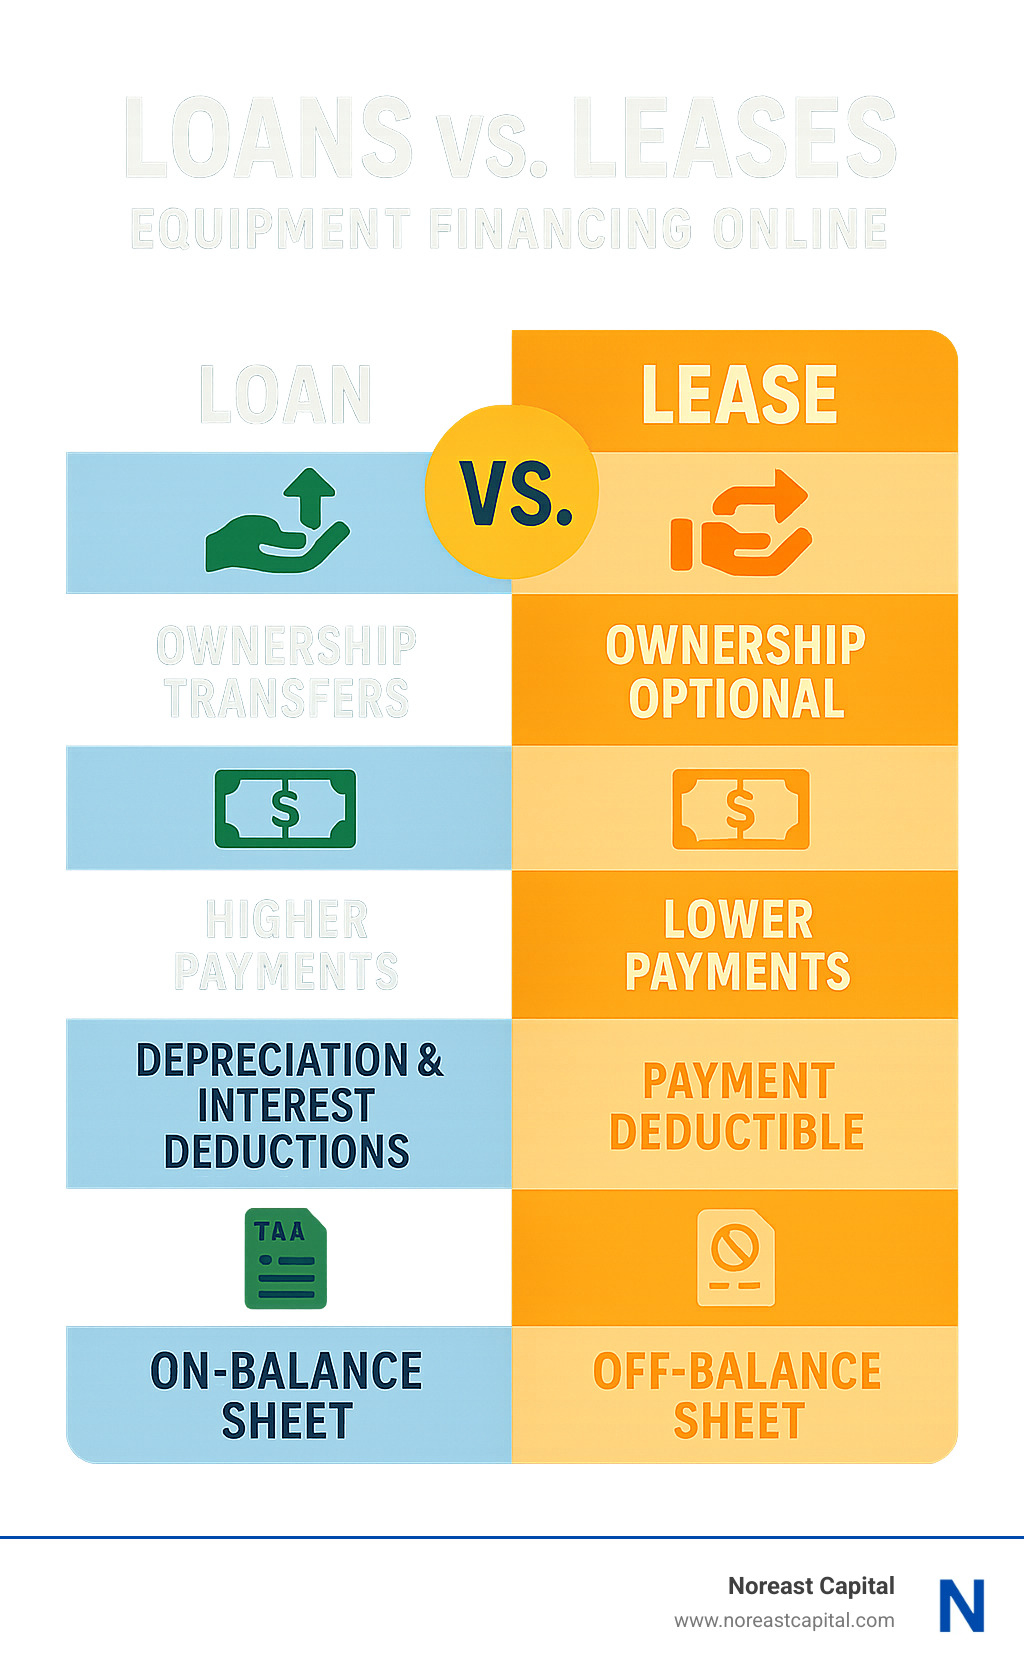
The ownership transfer difference is crucial to understand. With loans, you own the equipment from day one. With leases, you might have a purchase option at the end – often for $1 or fair market value – but ownership isn’t automatic.
Upgrade cycles matter more than many businesses realize. If you need to replace equipment every 2-3 years to stay competitive, leasing provides a clear exit strategy. But for equipment with longer useful lives – think 10+ years – loans often make more financial sense.
Cash flow impact varies between options. Leases usually require less money upfront and offer lower monthly payments, keeping more cash in your business. Loans might need down payments but build equity with each payment you make.
At Noreast Capital, we help businesses think through these decisions based on their specific situation. A construction company planning to use equipment for a decade might benefit from a loan, while a tech firm needing regular upgrades might prefer leasing.
More info about Equipment Financing vs Leasing
Calculating Total Cost with an Equipment Financing Online Calculator
Understanding the true cost of equipment financing online means looking beyond those monthly payment numbers. Modern online calculators make this analysis much easier, but you need to know what numbers to plug in and how to read the results.
The principal amount isn’t just the equipment cost. It includes delivery, installation, training, and any other soft costs you’re financing. Many businesses get surprised when they focus only on the equipment price and forget about these extras that can add 10-20% to the total.
Interest rates for equipment financing typically run from 6.25% to 25%, depending on your credit, the equipment type, and how long you want to finance it. Online platforms often show rate ranges, but your actual rate depends on your specific situation.
Fees can sneak up on you if you’re not careful. Watch for origination fees (usually 0.5-3% of the loan amount), documentation fees ($200-$500), processing fees, and early termination penalties for leases.
Section 179 tax benefits can dramatically change your real cost. This tax provision lets businesses deduct up to $1,160,000 in equipment purchases in the first year instead of spreading depreciation over many years. If you’re in the 25% tax bracket, that could save you $290,000 in taxes on a $1,160,000 equipment purchase.
Let’s look at a real example. Say you’re financing $100,000 in equipment at 8% interest over 5 years. Your monthly payment would be about $2,028, and you’d pay $121,680 total – that’s $21,680 in interest. But with Section 179 tax savings of $25,000 (assuming 25% tax bracket), your net effective cost drops to $96,680.
More info about Equipment Finance Calculator
Securing the Best Online Offer & Avoiding Pitfalls
Getting the best deal on equipment financing online isn’t just about finding the lowest rate – it’s about understanding the complete picture and avoiding costly mistakes that can haunt your business for years.
Rate shopping is your first line of defense against overpaying, but you need to do it smart. The beauty of online platforms is that most perform soft credit pulls initially, letting you compare offers without damaging your credit score.
Here’s the strategy that works: Apply to 3-5 lenders within a 14-day window. This keeps all hard credit inquiries grouped together, minimizing impact on your credit score. But don’t just look at interest rates – compare the APR (Annual Percentage Rate), which includes fees and gives you the true cost of borrowing.
Hidden fees are where many businesses get burned. An attractive 8% interest rate loses its appeal when you find a 3% origination fee, monthly servicing charges, and early termination penalties.
Watch out for application fees charged upfront. Legitimate lenders don’t need money before they approve your loan. Documentation fees over $500 are another red flag, and monthly servicing fees can add thousands to your total cost over time.
Balloon payments can be a cash flow time bomb. Some lenders offer attractively low monthly payments by pushing a large chunk of the principal to the end of the term. While this might help your monthly budget, make sure you have a solid plan for that final payment.
Cross-collateral clauses are particularly sneaky. Some lenders want to secure your equipment loan against other business assets. This might seem harmless, but it can complicate future financing and put additional assets at risk if things go wrong.
Your document checklist can make the difference between quick approval and frustrating delays. Keep your application complete and accurate – inconsistencies raise red flags with underwriters. Make sure your equipment quotes are current (less than 30 days old) and include all the details the lender needs.
Industry-specific programs often beat generic financing hands down. Lenders who specialize in your industry understand your unique needs and risks. Medical equipment financing might offer longer terms because medical devices last longer. Restaurant equipment programs might include seasonal payment options for businesses with fluctuating cash flow.
Heavy equipment financing requires special attention because of the higher stakes involved. Equipment condition and age matter more when you’re financing a $500,000 excavator versus a $5,000 printer. Consider the manufacturer’s warranty terms, resale value trends, and seasonal usage patterns.
More info about How to Finance Heavy Equipment
Common Mistakes When Using Equipment Financing Online
Even with all the convenience of equipment financing online, businesses still make mistakes that cost them money. The good news is that these pitfalls are completely avoidable once you know what to watch for.
Over-terming is the most expensive mistake I see. Yes, longer terms mean lower monthly payments, but they also mean paying thousands more in interest. A $50,000 loan at 8% costs $60,664 over 5 years but jumps to $73,024 over 7 years. That’s an extra $12,360 you’re throwing away for slightly lower monthly payments.
Match your loan term to the equipment’s useful life. Technology equipment should be financed for 2-4 years maximum – you don’t want to be making payments on obsolete computers. Vehicles typically work well with 3-5 year terms, while heavy machinery can justify 5-7 years.
Ignoring upgrade needs is particularly costly in our rapidly changing business environment. That state-of-the-art software system might be outdated in three years. For equipment that evolves quickly, consider shorter loan terms, lease options with upgrade provisions, or technology refresh programs.
Skipping tax advice can cost you thousands in missed deductions or poor timing decisions. Section 179 deductions, bonus depreciation, and lease payment deductibility all have specific rules that change regularly. A quick consultation with your accountant before finalizing financing can save you more money than the financing costs in the first place.
Poor vendor selection can turn a smooth financing process into a nightmare. Make sure your equipment vendor has established credit terms with your lender, can provide proper documentation, and has a solid track record of on-time delivery.
Frequently Asked Questions about Online Equipment Financing
When businesses first explore equipment financing online, they naturally have questions about how the process works and what to expect. Let me address the most common concerns with straight answers based on real experience.
How much can I borrow or lease online?
The beauty of equipment financing online is that there’s likely a solution for your business, whether you need $5,000 for office equipment or $5 million for a complete manufacturing line. Most online platforms focus on the sweet spot between $5,000 and $500,000, where automated systems work most efficiently.
Your borrowing capacity depends on three main factors. Credit scores play the biggest role – businesses with excellent credit (720+) can access the full range of financing options. If your credit sits in the fair range (620-720), you’ll typically qualify for amounts up to $250,000 or $500,000. Even businesses with credit challenges can often secure $50,000 to $100,000 to get started.
Monthly revenue creates the second boundary. Most lenders want your total debt payments to stay under 25-30% of monthly income. So if your business brings in $50,000 monthly, you might qualify for financing with payments up to $12,500-$15,000 per month.
The equipment itself sets the final limit. New equipment can often be financed at 80-100% of value, while used equipment typically maxes out at 70-90%. The key is how easily the lender could resell the equipment if needed.
How fast will I receive funds?
Speed is where equipment financing online really shines compared to traditional bank loans. What used to take weeks now happens in days or even hours.
Same-day approvals have become the standard for straightforward deals under $250,000. The automated systems can check your credit, verify your bank account, and approve your financing faster than you can finish your lunch break.
Funding typically happens within 24-48 hours once you’ve signed the paperwork. Here’s how it usually plays out: You apply and get approved on day one. You review and sign documents electronically that same day or the next. The lender wires money to your equipment vendor on day two or three. Your equipment starts shipping immediately after payment.
Several factors can speed things up or slow them down. Complete applications with all required documents move fastest. Your equipment vendor’s relationship with the lender can make a difference – established vendors often get paid the same day.
Can a startup with limited credit qualify?
Absolutely. Startups often need equipment most, and smart lenders have created programs specifically for new businesses. The process takes more work, but it’s definitely possible.
Startup programs recognize that new businesses operate differently than established ones. You’ll typically need to provide a personal guarantee, which means you’re personally responsible if the business can’t pay. Down payments are often higher – maybe 10-25% instead of zero down. Terms might be shorter initially, like 2-3 years instead of 5-7 years.
The documentation requirements are more extensive for startups. You’ll need personal credit reports for anyone guaranteeing the loan. A solid business plan with realistic financial projections helps tremendously. Proof of industry experience shows you know what you’re doing.
My advice for startups is to start smaller and build up. Get approved for $25,000-$50,000 initially, make payments on time, and establish a track record. Your capacity will grow as your business credit develops.
Conclusion
Equipment financing online has fundamentally transformed how businesses acquire the tools they need to grow and compete. The combination of speed, convenience, and competitive terms available through digital platforms makes equipment financing an essential tool for modern business management.
Capital Preservation remains the primary benefit of equipment financing. Rather than depleting cash reserves for equipment purchases, businesses can preserve working capital for inventory, payroll, marketing, and unexpected opportunities. This financial flexibility often means the difference between surviving economic downturns and thriving during growth periods.
Growth Enablement through equipment financing allows businesses to scale faster than internal cash generation would permit. A construction company can bid on larger projects with new equipment, a medical practice can serve more patients with additional diagnostic equipment, and a manufacturing business can increase capacity with new machinery – all without waiting to accumulate sufficient cash.
Online Speed Advantages cannot be overstated in today’s competitive environment. When a critical piece of equipment fails or a growth opportunity emerges, waiting weeks for traditional bank approval can mean lost revenue or missed opportunities. Online platforms delivering funding in 24-48 hours keep businesses moving at market speed.
Section 179 Tax Savings can make equipment financing cash-flow positive in the first year. With deductions up to $1,160,000 available for qualifying equipment purchases, many businesses find that tax savings exceed financing costs, effectively making equipment acquisition profitable from day one.
At Noreast Capital, we’ve witnessed thousands of businesses transform their operations through strategic equipment financing. From our offices in Annapolis, Baltimore, and Washington DC, we serve businesses nationwide, providing the capital equipment financing solutions that fuel American business growth.
The future of business equipment acquisition is digital, fast, and flexible. Whether you need construction equipment, medical devices, commercial vehicles, or technology solutions, equipment financing online provides the speed and convenience modern businesses demand.
Our unique approach focuses on partnership rather than just transactions. We understand that equipment financing is about enabling your business vision, not just moving money. That’s why we’ve structured our programs to preserve your cash flow while providing the tools you need to compete and grow.
Ready to experience the simplicity and speed of modern equipment financing? The next piece of equipment your business needs is just an application away.